Tag: superannuation

  • Transfer Balance Cap Australia 2026-27: The $2.1 Million Limit, Your Personal Cap, and the Mistakes That Cost Retirees

    Transfer Balance Cap Australia 2026-27: The $2.1 Million Limit, Your Personal Cap, and the Mistakes That Cost Retirees

    Australia’s transfer balance cap is $2.1 million for 2026-27. That’s the lifetime limit on how much super you can shift into the tax-free retirement phase, and it rose $100,000 on 1 July 2026 from the $2.0 million cap of 2025-26. Sounds simple — until you discover the cap that matters most isn’t the $2.1 million headline number at all. It’s your personal transfer balance cap, set the first time you start a retirement-phase pension, which may be lower than $2.1 million and can never be reset. Breach it and you’re looking at excess transfer balance tax of 15% the first time and 30% every time after that, plus a forced commutation of the excess. This guide walks through exactly how the cap works in 2026-27, with worked examples in real dollars, the mistakes that catch people out, and the planning windows the ATO’s rules actually give you.

    How the transfer balance cap works in 2026-27

    The transfer balance cap limits how much of your super can enjoy the zero-tax retirement-phase earnings environment. It was introduced on 1 July 2017 to stop people parking unlimited balances in tax-free pensions. Every time you move money into retirement phase — starting an account-based pension, receiving a reversionary death-benefit pension, or having a defined-benefit credit counted — a credit is recorded against your transfer balance account. Money moved back out (commutations to accumulation, lump-sum withdrawals) creates a debit.

    The account is a running ledger, not a snapshot. What matters is your highest ever credit balance, not your current balance. That’s the trap most people fall into: market growth after the money is in pension phase never creates a credit, but it also never frees cap space. Your personal cap is set, effectively, the first time you enter retirement phase — and it’s the highest-ever balance against that personal cap that determines whether you’ve breached.

    Key things that do not count:

    • Regular pension payments — the monthly or annual income you draw from your pension is not a debit and can’t be “re-credited” later.
    • Investment growth inside the pension — if your $2.1 million pension grows to $3 million, no breach has occurred. Growth is ignored for the cap.
    • Transition to retirement (TTR) pensions — these are not retirement-phase income streams, so starting one creates no credit (until it converts to retirement phase, typically at age 65 or on retirement).

    Transfer balance cap history

    Financial year General transfer balance cap
    2017-18 to 2020-21 $1.6 million
    2021-22 to 2022-23 $1.7 million
    2023-24 to 2024-25 $1.9 million
    2025-26 $2.0 million
    2026-27 $2.1 million

    A quirk worth noting: in July 2023 the cap jumped straight from $1.7 million to $1.9 million — there was never a $1.8 million step, because indexation happens in $100,000 increments tied to CPI movements, and the trigger simply landed at $1.9 million. If you come across an article claiming the cap is “$1.9 million as of 2026” — yes, at least one high-ranking guide is still saying exactly that — it’s stale. The general cap has been $2.0 million since 1 July 2025 and is $2.1 million from 1 July 2026.

    For the small number of Australians with defined-benefit pensions, the related defined benefit income cap for 2026-27 is $131,250 — that’s simply the general cap divided by 16. Defined-benefit pensions don’t move money the same way, so the law deems a credit equal to your annual pension income multiplied by 16. More on that in the examples below.

    Your personal transfer balance cap — step by step

    Here’s the concept that does the real work. Your personal transfer balance cap is set the first time you start a retirement-phase income stream, and it equals the general cap in force at that date. It then gets proportional indexation: when the general cap rises, your personal cap rises only on the portion you hadn’t used.

    1. Work out your used percentage. Divide the amount you transferred into retirement phase by the general cap at that time. If you started a $1.4 million pension when the cap was $2.0 million, you used 70%.
    2. Work out your unused percentage. That’s 100% minus the used percentage — 30% in this example.
    3. Apply indexation to the unused portion only. When the general cap rises by $100,000, your personal cap rises by 30% × $100,000 = $30,000. So your personal cap becomes $2.03 million — not $2.1 million.

    The brutal version: if you used 100% of your cap when you started (transferred $2.0 million under the $2.0 million cap), your personal cap is frozen at $2.0 million forever. You get none of the July 2026 indexation. That’s why some retirees who “maxed out” their pension in 2025-26 are stuck below the new headline number — and why starting slightly under the cap, when you can, preserves indexation.

    You can check your personal cap in ATO online services (myGov → ATO → Super → Transfer balance cap). If your fund has reported correctly, it’s sitting right there. If you need to model what a part-time return to work, a commutation, or a reversionary pension does to your cap, the super calculator can help you sanity-check the moving parts.

    Worked examples in 2026-27 dollars

    Example 1: Margaret’s personal cap across the indexation

    Margaret, 64, started an account-based pension in October 2025 with $1,400,000. The general cap at the time was $2,000,000.

    • Used percentage: $1,400,000 ÷ $2,000,000 = 70%
    • Unused percentage: 30%
    • On 1 July 2026, the general cap rose $100,000 to $2,100,000
    • Margaret’s indexation: 30% × $100,000 = $30,000
    • Margaret’s personal cap from 1 July 2026: $2,030,000

    She still has $630,000 of cap space (her personal cap of $2.03 million minus the $1.4 million she already holds in pension phase). If her unused percentage had been 0%, she’d be stuck at $2.0 million — a $100,000 difference in lifetime tax-free capacity.

    Example 2: the excess, and what it costs

    David started a pension in August 2026 with $2,280,000 — $180,000 over his $2.1 million personal cap. The ATO issues an excess transfer balance determination, and he must commute the excess within 60 days or the ATO will issue a commutation authority forcing his fund to do it.

    Separately, excess transfer balance tax applies to the notional earnings on the excess — the earnings the excess is deemed to have made, compounding daily at (90-day bank bill yield + 7 percentage points) ÷ 365 until the excess is crystallised. Assume the excess sat for 90 days and the notional rate was roughly 10.2% per annum:

    • Notional earnings: $180,000 × 10.2% × (90 ÷ 365) ≈ $4,500
    • First breach: 15% × $4,500 = $675 in excess transfer balance tax
    • Second and subsequent breaches: 30% — the same fact pattern the second time costs $1,350, and it keeps compounding

    Two lessons: the tax itself looks small, but it applies on top of having to commute the excess, and the 30% rate means a repeated breach hurts twice as much. Get the commutation done inside the 60 days.

    Example 3: the couple strategy — $4.2 million, not $2.1 million

    The cap is per person, not per household. A couple where each spouse has a $2.1 million personal cap can hold $4.2 million in tax-free pension phase between them. This is where contribution splitting and spouse contributions years before retirement genuinely pay off: every dollar contributed to the lower-balance spouse’s account (rather than topping up the higher earner’s) is a dollar of future tax-free pension capacity that would otherwise be stranded in accumulation phase, where earnings are taxed at 15%.

    If you’re the higher earner and your super is at $2.0 million while your spouse’s is at $400,000, splitting contributions now builds two usable caps instead of one wasted one. Our income tax calculator can help model the tax cost of the salary-sacrifice contributions you’d use to do it.

    Example 4: the 30 June trap that kills your non-concessional cap

    Your total super balance (TSB) on 30 June 2026 decides your non-concessional contribution (NCC) eligibility for all of 2026-27. If your TSB is $2.1 million or more, your NCC cap is zero — nothing. The bring-forward tiers for 2026-27 are:

    TSB on 30 June 2026 NCC cap for 2026-27
    Less than $1.84 million $390,000 over 3 years (bring-forward)
    $1.84 million to less than $1.97 million $260,000 over 2 years
    $1.97 million to less than $2.1 million $130,000 (annual cap only)
    $2.1 million or more Nil

    Now the trap: your TSB is $2,090,000 in late June 2026. On 28 June you make a $15,000 non-concessional contribution — a perfectly ordinary top-up. On 30 June your TSB is $2,105,000. You have just crossed $2.1 million, and your entire 2026-27 NCC eligibility is gone. That single June contribution cost you up to $130,000 of future contribution capacity. Check your TSB before making late-June contributions if you’re anywhere near the boundary.

    Example 5: pension payments vs commutation — the $60,000 choice

    You’ve breached your cap by $60,000 and need to bring your transfer balance account back down. Two ways to take $60,000 out of the pension:

    • As regular pension payments: no debit is created. Your transfer balance account doesn’t move. The breach stays.
    • As a partial commutation (lump sum): a $60,000 debit is created, reducing your transfer balance account by $60,000. The breach is cleared.

    This is the single most misunderstood mechanic in the whole system: regular pension income does not reduce your cap usage. Only commutations do. When you’re managing an excess, take it as a commutation, not as pension payments. (Note the debit can never take your transfer balance account below zero, and it doesn’t increase your personal cap — it just brings the account balance back within it.)

    Example 6: the reversionary 12-month planning window

    When your spouse dies and a reversionary pension automatically continues to you, the credit to your transfer balance account generally arises 12 months after the date of death — not immediately. That’s a genuine planning window. Suppose you already have $1.9 million in your own pension and your late spouse’s reversionary pension is worth $600,000. In 12 months, your transfer balance account will jump to $2.5 million — $400,000 over a $2.1 million cap.

    The window lets you commute part of your own pension back to accumulation (creating debits) before the reversionary credit lands, or take advice on restructuring. Without the window, the credit would hit instantly and you’d be in breach with a 60-day clock running while grieving. Don’t waste it.

    Example 7: defined-benefit credit — $80,000 × 16

    Tom receives a defined-benefit pension of $80,000 per year. The credit to his transfer balance account is $80,000 × 16 = $1,280,000. That leaves him $820,000 of space under a $2.1 million cap for an account-based pension alongside it. Note the defined benefit income cap of $131,250 for 2026-27 — income above that threshold is taxed less concessionally, so high defined-benefit pensions have their own separate boundary to watch.

    Example 8: Division 296 meets the transfer balance cap

    Priya has a total super balance of $3.2 million, with $2.1 million in retirement-phase pension and $1.1 million in accumulation. Is she in trouble?

    • Transfer balance cap: fine. Only $2.1 million of credits against her $2.1 million personal cap. The $1.1 million in accumulation creates no credits, and growth on the pension doesn’t either.
    • Division 296: bites. From 1 July 2026, the extra 15% tax on earnings applies to the portion of her balance above $3 million — so earnings attributable to roughly $200,000 of her balance attract the additional tax.

    The two regimes measure different things: the transfer balance cap polices what’s in tax-free pension phase; Division 296 polices total balance. You can pass one and fail the other. For the full Division 296 breakdown, see our guide to Division 296 super tax in Australia.

    Common mistakes

    • Assuming the headline cap is your cap. If you started your pension when the general cap was $1.9 million and used all of it, your personal cap is $1.9 million — $200,000 below today’s headline number.
    • Taking pension payments to fix a breach. As Example 5 showed, only commutations create debits. Regular payments leave the breach untouched.
    • Panic-selling when growth pushes a pension past $2.1 million. Growth after the credit is irrelevant. A $2.1 million pension that grows to $3 million has not breached anything.
    • The late-June NCC that trips the TSB test. One contribution on 28 June can zero out a full year of non-concessional eligibility.
    • Ignoring the fund’s reporting. Your transfer balance account is built from what your fund reports to the ATO. Wrong values in, wrong cap position out — check it in ATO online services.
    • Trusting stale guides. Anything quoting “$1.9 million as of 2026” hasn’t been updated since the July 2025 indexation, let alone July 2026.
    • Forgetting the transfer balance cap isn’t the only ceiling. Division 296, the NCC caps, and the defined benefit income cap all run on their own tracks.

    Tips for 2026-27

    • Leave a buffer when you start. Commencing a pension at 95% of the cap instead of 100% preserves indexation on the unused 5% — free lifetime cap space.
    • Equalise spouses early. Contribution splitting and spouse contributions in your 40s and 50s build two full $2.1 million caps instead of one stranded balance.
    • Diary the reversionary date. The 12-month window after a spouse’s death is the most valuable planning period the rules give you — use it to commute and restructure before the credit lands.
    • Commute, don’t just draw, when managing an excess. Only commutations reduce the transfer balance account.
    • Check your TSB in mid-June before any late-June non-concessional contributions near the $2.1 million boundary.
    • Reconcile your fund’s reporting annually. A misreported pension commencement value can manufacture a phantom breach — or hide a real one.
    • Model the whole picture. The transfer balance cap interacts with contribution caps, withdrawal tax, and death benefits — see our guides on super contribution caps for 2026-27, super withdrawal tax, and super death benefits tax.

    Frequently asked questions

    Does investment growth inside my pension breach the cap?

    No. Credits are only created when money moves into retirement phase. Once it’s there, growth is ignored for transfer balance purposes. A pension that started at $2.1 million and grows to $3 million has not breached — and you don’t need to commute the growth out.

    Can I transfer my unused transfer balance cap to my spouse?

    No — the cap is strictly personal and non-transferable. If you die with unused cap space, it dies with you. The practical workaround is lifetime planning: contribution splitting and spouse contributions while you’re both alive build up both spouses’ balances, so each of you can use your own $2.1 million cap.

    What if my fund reported the wrong value to the ATO?

    Your transfer balance account is only as accurate as your fund’s reporting. If the commencement value is wrong, your cap position is wrong — you could be flagged for a breach that never happened, or miss a real one. Contact your fund to correct the reporting, then check that the correction flows through in ATO online services (myGov). Keep the fund’s written confirmation; if a determination is issued on bad data, you’ll need it to have it revoked.

    What happens if I ignore an excess transfer balance determination?

    You have 60 days to commute the excess after the determination issues. If you don’t, the ATO issues a commutation authority directly to your fund, forcing the release — you lose control of which pension is commuted and when. The excess transfer balance tax on the notional earnings applies regardless. Ignoring it is the worst option on every axis.

    Does starting a transition to retirement pension use my cap?

    No. A TTR pension is not a retirement-phase income stream, so starting one creates no credit against your transfer balance account. The credit only arises if and when it converts to retirement phase (for example, when you turn 65 or notify the fund of retirement). This is a genuine timing tool: you can be drawing a TTR pension while your transfer balance cap sits completely untouched.

    Can I start a second pension after commuting the first?

    Yes — commuting creates a debit, and you can commence a new pension later. But your personal cap never resets: the new pension’s credit is measured against the same personal cap, and it’s your highest ever balance that counts for breach purposes. Commuting and restarting doesn’t launder a breach away.

    The bottom line

    The transfer balance cap for 2026-27 is $2.1 million — but the number that governs your retirement is your personal cap, set the day you first entered retirement phase and indexed only on what you left unused. The people who get this right do three things: leave a buffer when they commence, equalise balances between spouses years in advance, and treat commutations — not pension payments — as the lever that moves the account. The people who get it wrong usually discover the rules from a determination letter, with 60 days on the clock. Check your position in ATO online services now, while it’s still a planning exercise rather than a compliance one. The ATO’s own guidance is at ato.gov.au.
  • Is Paid Parental Leave Taxed in Australia? 2026-27 Guide

    Is Paid Parental Leave Taxed in Australia? 2026-27 Guide

    Quick answer: yes — Paid Parental Leave is taxable income in Australia. Every dollar of Parental Leave Pay lands in your taxable income for the year, and the ATO taxes it at your marginal rate like ordinary wages. The part that catches people out isn’t the rule itself — it’s the 15% flat tax Services Australia withholds by default when the payment comes directly from them. That 15% is just a withholding guess, not your tax rate. Depending on what else you earned that year, it can leave you with a surprise refund… or a surprise bill of several thousand dollars. Below: the 2026-27 rates, both payment paths, and the maths in real dollars.

    How Parental Leave Pay works in 2026-27

    Parental Leave Pay (PPL) is the Australian Government payment for parents of a newborn or newly adopted child, administered by Services Australia. For children born or adopted on or after 1 July 2026, the scheme reached its full size:

    2026-27 detail Figure (before tax)
    Daily rate $200.94 (the national minimum wage)
    Weekly equivalent (5-day week) $1,004.70
    Fortnightly $2,009.40
    Maximum entitlement 130 days (26 weeks)
    Full entitlement, total $26,122.20
    Reserved for your partner 20 days — use it or lose it ($4,018.80)
    Superannuation on PPL 12% paid by the ATO after the financial year (~$3,135 on the full entitlement)

    The rate follows the minimum wage each 1 July, so leave straddling 30 June is paid at two daily rates. Days are flexible — blocks or single days, including weekends, any time before your child’s second birthday. An income test also applies (the published individual threshold is $186,487 — indexed, so confirm the current figure on Services Australia), plus a work test of 330 hours in 10 of the 13 months before the birth.

    The two ways the money reaches you — and why it matters for tax

    There are two payment paths, and they withhold tax differently:

    1. Through your employer. If you’ve been with your employer 12+ months and take a block of 8+ weeks, they may have to pass the government payment through payroll. Services Australia reimburses them — but for you it arrives like ordinary wages, with PAYG withheld at your normal payroll rate.
    2. Directly from Services Australia. If the employer path doesn’t apply, Services Australia pays you directly — and withholds a flat 15% from every payment unless you ask for a different rate.

    Either way, the payment is taxable. The only difference is the withholding mechanics — and as the worked examples below show, that difference is where the surprises live.

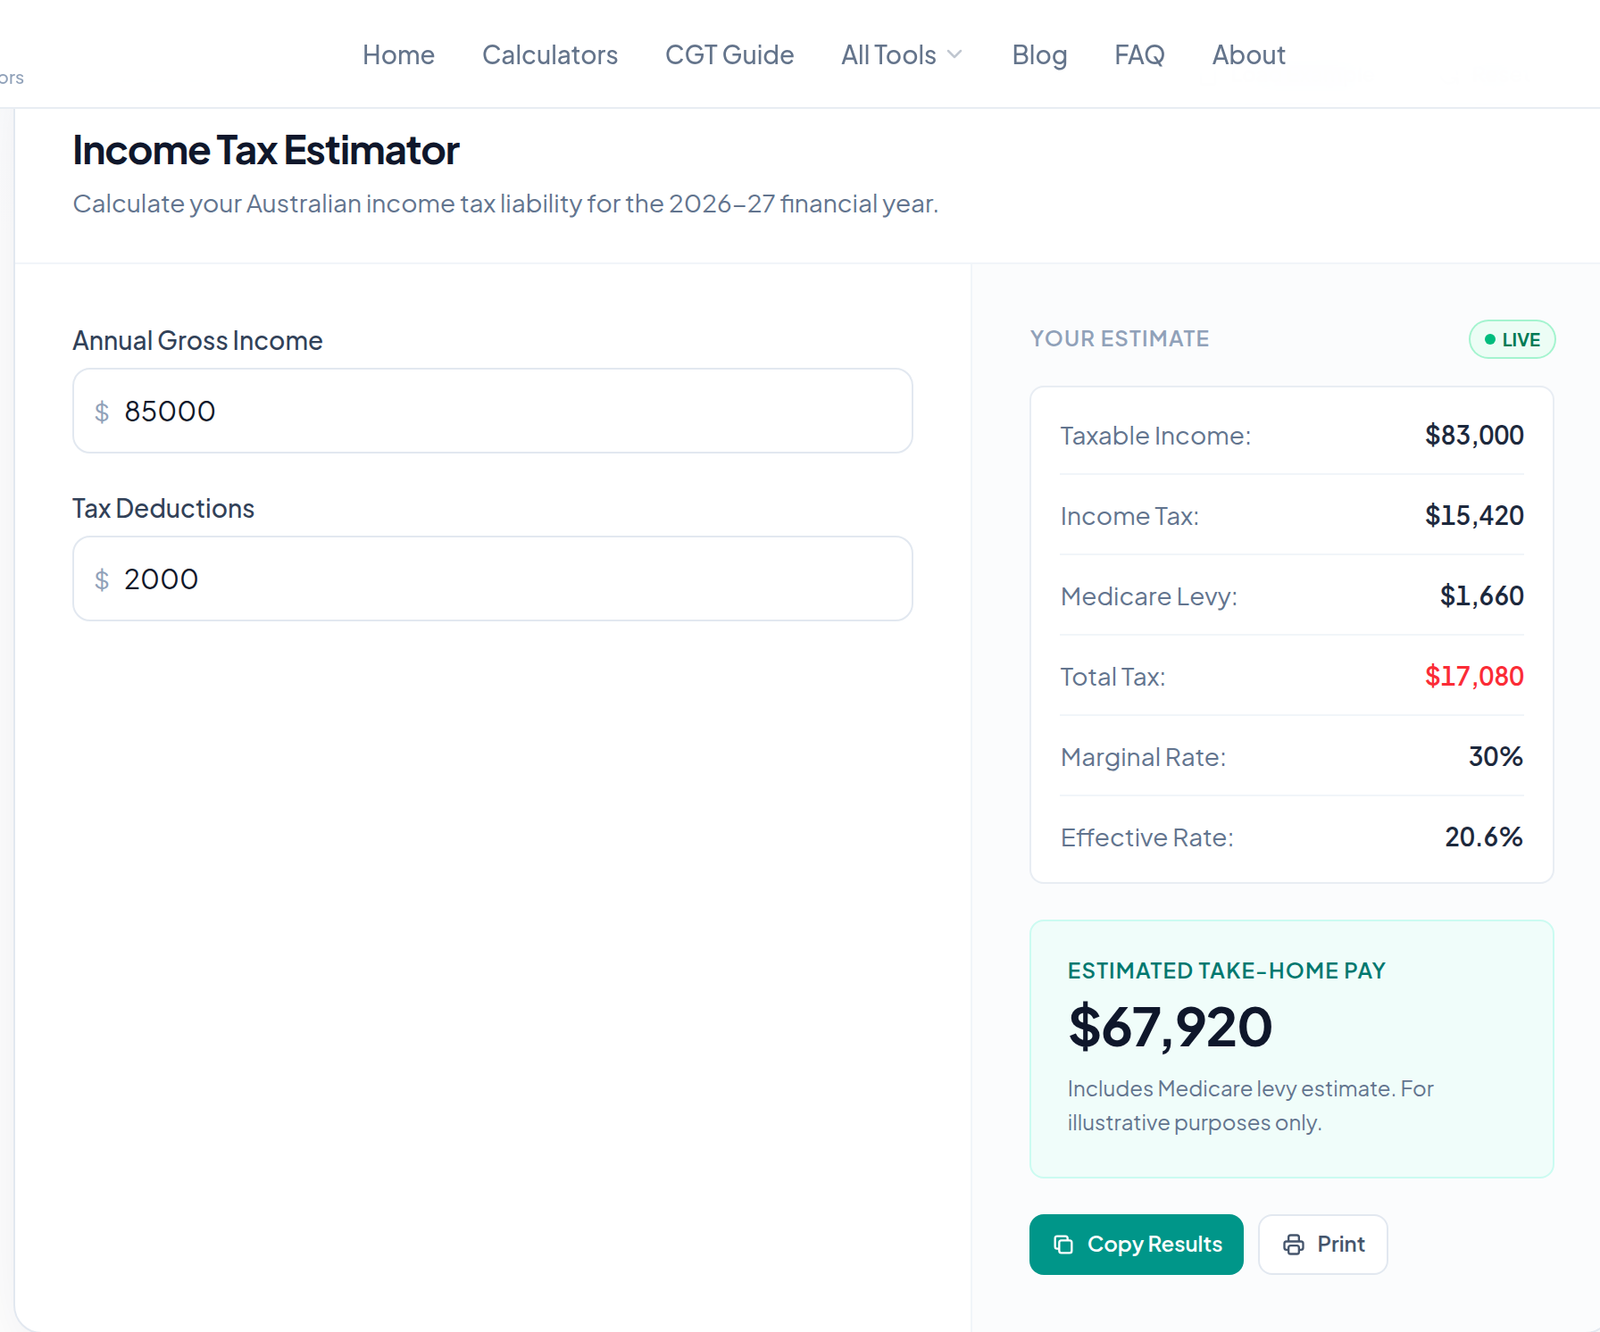
    Income tax calculator showing $15,420 income tax on $83,000 taxable income for 2026-27
    Our income tax calculator with $85,000 income and $2,000 deductions (2026-27 rates): $17,080 total tax.

    How the tax on PPL is actually worked out

    Think of it in two separate steps, because confusing them is the #1 mistake:

    Step 1 — withholding (the guess). Tax taken from each payment before it reaches you: either your employer’s payroll tables or Services Australia’s flat 15%. Not your tax bill — a prepayment credited against it.

    Step 2 — your actual liability (the truth). At tax time, the ATO adds your PPL to everything else you earned and taxes the total at the 2026-27 marginal rates: 0% to $18,200, then 15% to $45,000, 30% to $135,000, 37% to $190,000 and 45% above — plus the 2% Medicare levy where it applies.

    Crucially, your PPL stacks on top of your other income. It doesn’t get its own concessional rate — the last dollar of PPL is taxed at whatever marginal rate your total income puts you in. That’s why the same $26,122 of PPL can produce a refund for one parent and a $4,000+ bill for another.

    On your return, PPL is usually pre-filled in myTax — via Single Touch Payroll if it came through your employer, or a payment summary from Services Australia if it came direct. Check it’s there; don’t assume.

    Worked example 1: PPL as your only income — the refund surprise

    Meet Priya. She takes the full 130 days in 2026-27 and has no other income that year. Here’s her position:

    • Gross PPL: 130 × $200.94 = $26,122.20
    • Tax withheld (15% flat): $26,122.20 × 15% = $3,918.33
    • Actual income tax: ($26,122.20 − $18,200) × 15% = $1,188.33
    • Medicare levy: $0 — $26,122 sits under the 2026-27 single low-income threshold of $28,011
    • Result: a refund of about $2,730

    Why the refund? The 15% withholding ignores the $18,200 tax-free threshold — it taxes the first dollar, while the ATO taxes only dollars above $18,200. If PPL is most or all of your year’s income, the flat withholding over-withholds and the difference comes back. (Exception: a HECS/HELP debt can divert the refund — see below.)

    Worked example 2: salary plus PPL — the shortfall bill

    Now meet Daniel. Across 2026-27 he earned $85,000 all up — part salary, part Parental Leave Pay — and claims $2,000 of work-related deductions. Run it through our income tax calculator (screenshot below):

    • Taxable income: $85,000 − $2,000 = $83,000
    • Income tax: $4,020 + ($83,000 − $45,000) × 30% = $15,420
    • Medicare levy: 2% × $83,000 = $1,660
    • Total liability: $17,080

    Now the withholding sting. Say $26,122 of Daniel’s $85,000 was PPL paid directly by Services Australia, with only the default 15% withheld: $3,918. But that PPL stacks on top of his salary at his 30% marginal rate — the real tax on the PPL portion is $7,837 of income tax plus $522 of Medicare levy = $8,359.

    Shortfall on the PPL alone: roughly $4,441. His employer’s PAYG withholding on the salary was roughly right; the entire bill comes from the under-withheld PPL. This is the single most common PPL tax shock, and it’s entirely predictable once you see the stacking.

    The HECS/HELP sting nobody warns you about

    Here’s the trap that turns even Example 1’s refund into a bill. Parental Leave Pay counts as repayment income for HECS/HELP purposes — it sits inside your taxable income, which is the base the ATO uses for compulsory student-loan repayments. And the 15% Services Australia withholds does not cover HELP at all.

    The real-world version: a parent on maternity leave earns less than usual, expects a refund, then discovers the ATO applied $3,000 of it to their student debt — with a bill on top — because PPL pushed their repayment income over the threshold. If you have a HELP debt, check your TFN declaration has the HELP box ticked, and consider raising the withholding rate on your PPL via myGov. Our HECS/HELP repayment guide has the current thresholds and rates.

    Super is now paid on your PPL — the details that matter

    For children born or adopted from 1 July 2025, the ATO pays a 12% superannuation contribution on your Parental Leave Pay — the Paid Parental Leave Super Contribution (PPLSC). On the full 130-day entitlement that’s 12% × $26,122.20 ≈ $3,135 extra in your super. The fine print:

    • Timing: it’s paid after the financial year ends. PPL paid in 2026-27 won’t land in your fund until after 30 June 2027 — don’t go looking for it in December.
    • Tax treatment: it’s a concessional contribution, taxed at 15% inside your fund — same as employer SG.
    • It counts toward your $32,500 concessional cap. Usually irrelevant while you’re on leave (employer SG drops too), but heavy salary-sacrificers should allow for the ~$3,135 in the year the fund receives it.
    • It’s not counted as income for Centrelink, family assistance or child support purposes.
    • It needs your TFN. If your super fund doesn’t have your tax file number, or your name and address don’t match across Services Australia, the ATO and your fund, the contribution can go astray. Check it in myGov (ATO online → Super).

    The interaction checklist: everywhere else PPL lands

    PPL doesn’t just affect your income tax return. Because it’s ordinary taxable income, it flows into every income-tested calculation in the system:

    Calculation How PPL affects it
    Medicare levy (2%) Applies to your total taxable income including PPL. Under the low-income thresholds (singles $28,011 in 2026-27) you may pay nothing — but the PPL still counts toward the threshold test.
    Medicare levy surcharge PPL counts in your income for surcharge purposes. Only bites if your total pushes you over $105,000 (singles) without hospital cover.
    HECS/HELP repayments PPL is part of your repayment income. Can trigger or increase a compulsory repayment the 15% withholding never covered.
    Child Care Subsidy & Family Tax Benefit You must include PPL in your family assistance income estimate — Services Australia says so explicitly. Underestimating means a reconciliation debt at balancing time.
    Income support payments PPL counts as income for income-support calculations (unlike FTB itself, which isn’t taxable).
    Super contribution (PPLSC) Deliberately excluded — the 12% super top-up is not counted as income for Centrelink or family assistance.

    Six mistakes that cost parents money

    1. Assuming PPL is tax-free. It’s the most common myth — and yes, some websites still claim it. Parental Leave Pay is assessable income, full stop. The ATO’s withholding law was specifically amended to cover it.

    2. Treating the 15% withheld as your tax rate. It’s a default prepayment. Your actual rate is your marginal rate on total yearly income — which for anyone who worked part of the year is almost certainly higher than 15%.

    3. Forgetting the stacking. PPL doesn’t get taxed in isolation at some gentle rate. It piles on top of your salary, and every dollar of it can be taxed at your top marginal rate.

    4. The HECS blind spot. The 15% withholding covers income tax only. If you have a student debt, the compulsory HELP repayment is a separate impost the withholding never anticipated.

    5. Leaving PPL out of the CCS/FTB income estimate. Family assistance is reconciled against actual income at year end. An estimate that “forgot” $26,000 of PPL becomes a debt notice.

    6. Thinking employer-paid and government-paid PPL are taxed differently. They’re not — both are taxable. Only the withholding method differs (normal payroll rates vs flat 15%). The end liability is identical.

    Five tips to get the numbers right

    1. Vary the withholding rate if you’ll have other income. Once your Centrelink record is linked to myGov, you can change the 15% deduction online. If Daniel from Example 2 had raised his to 32%, the $4,441 bill would never have arrived.

    2. Time your days across 30 June deliberately. PPL is taxed in the financial year it’s paid, and days can spread over two years. Loading more days into the lower-income year genuinely cuts the tax — just note the daily rate changes each 1 July.

    3. Lump sum or weekly makes no difference to the total. Whether Services Australia pays you weekly or your employer passes on a lump sum, your liability is driven by total income for the year, not the payment pattern. (Which year it lands in is what matters — see tip 2.)

    4. Match your details everywhere for the super contribution. Name, address and TFN need to agree across Services Australia, the ATO and your super fund, or the 12% PPLSC can miss your account. Check myGov after 30 June.

    5. If PPL is your main income, expect money back — and check the pre-fill. As Example 1 shows, the flat 15% over-withholds when you have little other income. Make sure the PPL appears correctly in myTax before you lodge; a missing pre-fill is your mistake to catch, not the ATO’s.

    One more timing note for planners: if you’re weighing extra income from a second job against leave days in the same year, remember both stack at your marginal rate — model the combined figure, not each in isolation.

    Frequently asked questions

    Centrelink only withholds 15% — is that my actual tax rate, or will I owe more?

    It’s just a default withholding, not your tax rate. PPL is taxed at your marginal rate on total yearly income. If you earned salary as well, 15% almost certainly under-withholds — Example 2 shows a ~$4,441 shortfall on exactly this pattern. Request a higher rate through myGov.

    Is government PPL treated differently from my employer’s paid parental leave for tax?

    No. Both are taxable income. The only difference is withholding: government-paid PPL via Services Australia has 15% withheld by default; employer-paid (or employer-passed-through) PPL goes through normal payroll withholding like ordinary wages. Both are declared on your tax return and end up taxed identically.

    If I take my PPL as a lump sum instead of weekly payments, do I pay more tax?

    No — your total tax follows total income for the year, not the payment pattern. Weekly, fortnightly or lump sum all reconcile to the same liability. What does matter is which financial year the money lands in.

    Will Paid Parental Leave trigger a HECS/HELP repayment?

    It can. PPL forms part of your repayment income, so it can push you over the compulsory repayment threshold (or increase the repayment rate) even in a year you earned less than usual. The 15% Services Australia withholds doesn’t cover HELP — this is the classic surprise where an expected refund gets diverted to a student debt with a bill on top.

    Do I need to include PPL in my income estimate for Family Tax Benefit or the Child Care Subsidy?

    Yes. Services Australia requires PPL to be included in your taxable-income estimate for family assistance, and it counts as income in CCS calculations. If your estimate is too low, you’ll face a reconciliation debt when payments are balanced at year end — update the estimate as soon as your PPL starts.

    When is the super paid on my PPL, and how do I check it arrived?

    The ATO pays the 12% super contribution after the financial year the PPL was paid in — so for 2026-27 PPL, expect it after 30 June 2027. Check myGov (ATO online services → Super) and your fund’s transaction list for an ATO-sourced contribution. If it’s missing, check the timing first, then that your TFN and details match across Services Australia, the ATO and your fund.

    The bottom line

    Paid Parental Leave is taxable income — that part is simple. Everything expensive about it comes from the gap between the 15% withheld and your actual marginal rate. If PPL dominates your year, that gap hands you a refund (around $2,730 on the full entitlement with no other income). If you also worked, the same gap hands you a bill (around $4,400 when PPL stacks at 30%). Add the HECS overlay, the family-assistance estimates and the super timing, and you have the complete picture — in numbers your return will actually match.

    Verification: rates and rules checked against Services Australia’s tax-deduction guidance (15% default withholding, changeable via myGov), Services Australia’s Parental Leave Pay pages (PPL is taxable; include it in family assistance estimates), the ATO’s withholding provisions for parental leave pay (s 12-110, Sch 1 Taxation Administration Act), and the 2026-27 payment figures ($200.94/day, 130 days, 12% PPLSC). Brackets per the 2026-27 income tax rates; Medicare thresholds per the 2026-27 Medicare levy guide; concessional cap per the 2026-27 super caps guide. Rates change — confirm before acting. Not personal tax advice.

  • Downsizer Contribution Australia: $300k Super Boost When You Sell Your Home (2026-27)

    Downsizer Contribution Australia: $300k Super Boost When You Sell Your Home (2026-27)

    Sell your home at 55 or older and the tax rules let you move up to $300,000 per person — $600,000 for a couple — into super, on top of every other contribution cap. No work test. No balance test. No tax on the way in. The price of admission is a strict 90-day deadline from settlement, a one-page ATO form your fund must hold before or when you contribute, and a one-shot-per-lifetime rule almost everyone misunderstands. Here is how it all works in 2026-27, including the Division 296 wrinkle the other guides are not mentioning.

    How the downsizer contribution works

    A downsizer contribution is a special class of super contribution tied to a home sale. Introduced in 2018, the age threshold dropped from 60 to 55 in January 2023, which opened it to a much bigger group of pre-retirees.

    Compared with a normal after-tax contribution, it is strikingly generous:

    • $300,000 per person, outside the normal caps. It does not count towards the 2026-27 concessional cap ($32,500) or non-concessional cap ($130,000), and it neither triggers nor uses up the bring-forward rule.
    • No work test and no upper age limit. A fully retired 80-year-old can make one.
    • No total super balance test on making the contribution — people whose balances block ordinary after-tax contributions can still use it.
    • No 15% contributions tax on entry. It enters as a non-concessional contribution.
    • You do not have to buy a smaller home. Despite the name, there is no requirement to downsize or even to buy another home. Sell and rent, sell and upsize, move in with family — all fine.

    One ceiling to note: a couple’s combined contributions cannot exceed the total sale proceeds. Sell for $500,000 and the pair of you can contribute at most $500,000 between you.

    The official eligibility rules

    The ATO requires all seven of these:

    Rule Requirement
    Age 55 or older when you make the contribution — not when you sell.
    Ownership You and/or your spouse owned the home for 10+ years before the sale.
    Main residence test The sale qualifies for the main residence CGT exemption, fully or partially. Homes bought before 20 September 1985 must be ones that would have qualified.
    Property type An Australian residential building — not a caravan, houseboat or mobile home. Vacant land does not qualify.
    One shot You have never previously made a downsizer contribution (from another home’s sale or a part sale).
    Timing Contribute within 90 days of receiving the proceeds (usually settlement), unless the ATO grants an extension.
    Paperwork Your fund holds the Downsizer contribution into super form (NAT 75073) before or when you contribute.

    Spouse stacking: $600,000 from one sale

    Both spouses can each contribute up to $300,000 from the same sale — even if only one of them is on the title. The non-owning spouse just has to meet the other conditions. So if the house is entirely in your partner’s name, you can still put $300,000 of the proceeds into your own super account.

    There are also provisions for harder cases: if the spouse who held the ownership interest dies, you can count their ownership period — including time the home sits in the deceased estate — towards your 10-year test, and transfers between spouses on relationship breakdown are accommodated. Messy ownership history is worth checking with your fund rather than assuming you fail.

    What “one shot” actually means

    One downsizer contribution per person, ever. Not one per home — one.

    But it does not mean what at least one major guide claims: selling a home without contributing does not burn your turn. Sold at 58 and put nothing in? Sell a different home at 68 and you can still use the measure. The test is whether you have previously made a downsizer contribution.

    The real trap runs the other way: contribute less than $300,000 from a sale and you cannot top it up later from another sale. Within the original 90-day window, though, you can make several contributions — across different funds if you like — totalling up to $300,000, with a separate form for each payment.

    Does the home have to be your main residence when you sell?

    No. It must have qualified for the main residence CGT exemption at some point — fully or partially. A home you lived in for 12 years then rented out for 8 can still qualify, provided the sale attracts at least a partial exemption. Former family homes turned rentals are a common qualifying case people assume are excluded. If the exemption mechanics are hazy, read our guides to CGT on property and the main residence exemption before you list.

    Step by step: sell, form, contribute

    1. Confirm your fund accepts downsizer contributions before settlement, so you are not scrambling later.
    2. Note the settlement date. The 90-day clock runs from when you receive the proceeds — usually settlement day, not exchange. A long settlement buys you time.
    3. Complete the ATO form — the Downsizer contribution into super form (NAT 75073), or your fund’s equivalent.
    4. Give the form to your fund before or with the money. Skip this and the fund may code the money as an ordinary non-concessional contribution, which can breach your 2026-27 contribution caps and trigger excess-contributions tax.
    5. Transfer within 90 days of receiving the proceeds — EFT, BPAY or cheque, however your fund takes voluntary contributions.
    6. Verify the label. Confirm the fund recorded it as a downsizer contribution, not a personal one. Some people check ATO online services after their return is lodged, because a mislabel can generate an excess-contributions determination.

    What if 90 days is not enough?

    Ask the ATO for an extension of time. Extensions are available for genuine delays — drawn-out settlements, legal disputes, a build that is not finished — and advisers report the ATO being pragmatic when asked early; one practitioner secured an 18-month extension for a client simply by phoning ahead. Apply as soon as possible, ideally inside the original 90 days, and never contribute late without an approved extension. You cannot use an extension to manufacture eligibility, such as reaching age 55.

    Worked example: $1.2 million sale, $600,000 into super

    Margaret (63) and David (61) from Brisbane bought their family home in 2001 for $320,000, lived in it throughout, and sell in October 2026 for $1,200,000, settling 14 November 2026.

    CGT: main residence for the entire ownership period means the sale is fully exempt — no CGT on the $880,000 gain. The $1.2 million is theirs in full.

    The contributions: each already holds $450,000 in super. By early February 2027 (inside the 90 days) each lodges a NAT 75073 and contributes $300,000 — $600,000 combined.

    • No contributions tax on entry; no dent in their 2026-27 concessional or non-concessional caps. David can still stack carry-forward concessional contributions from unused prior-year cap on top.
    • New balances of $750,000 each — well under the $2.1 million transfer balance cap and far from the $3 million Division 296 threshold.
    • Both are over 60, so in a retirement-phase pension the earnings are tax-free and withdrawals are tax-free. Under 60 with no condition of release met, the contribution is preserved — you cannot pull it back out. See super withdrawal tax rules for detail.

    Inside vs outside super: say the $600,000 earns 6% a year — $36,000 of income. In a personal account at a 32.5% marginal rate, that costs about $11,700 in tax (keeping $24,300). Inside super’s accumulation phase at 15%, the tax is $5,400 (keeping $30,600) — roughly $6,300 a year better off, compounding annually, with a bigger gap once the money moves to a tax-free pension. Run your own numbers on our super calculator.

    The 2026-27 stacking year: up to $722,500 at once

    Because the downsizer sits outside the normal caps, one eligible person in 2026-27 can combine a $300,000 downsizer contribution, a $390,000 bring-forward non-concessional contribution (three years of the new $130,000 cap, balance tests permitting), and up to $32,500 of concessional contributions — $722,500 into super in a single year. A couple could theoretically move $1.445 million. That is a ceiling, not a target: the bring-forward has its own balance tests and Division 296 starts biting near $3 million. But it shows why advisers call the downsizer the crown jewel of late-stage super planning.

    Division 296: the new 2026-27 wrinkle

    From 1 July 2026, Division 296 adds a personal tax on earnings attributable to the slice of your total super balance above $3 million — an extra 15% on the $3m–$10m band, plus another 10% above $10m.

    The interaction the other guides miss: a downsizer contribution counts towards your total super balance. Not towards the contribution caps — towards the balance. Sitting at $2.85 million, a $300,000 downsizer takes you to $3.15 million and into Division 296 on the excess. For most people this is irrelevant, but near $3 million it turns the decision into a calculation rather than a reflex: get advice first, because the contribution cannot be undone.

    Common mistakes

    • Missing the 90-day deadline. Diary the settlement date the day contracts go unconditional; if delay looms, phone the ATO before the window closes.
    • Money without the form. No NAT 75073 with the fund at contribution time, no downsizer treatment — and possibly an excess-contributions surprise later.
    • Locking out a spouse. The partner not on the title can still contribute their own $300,000. Couples regularly leave that capacity on the table.
    • Trying to claim a deduction. Downsizer contributions are not deductible — they are after-tax money, untaxed on entry, and that is the deal.
    • Exceeding the proceeds. Combined contributions cannot top the sale price: on a $500,000 sale, $300,000 each is not available.
    • Forgetting preservation. At 55–59 with no condition of release met, the money is locked in. Do not contribute cash you might need next year.
    • Ignoring the Age Pension. Your home is assets-test exempt; the proceeds and the super balance generally are not. A $600,000 contribution can shrink or remove pension entitlements, and deemed income can hit the income test. Model it before you sell.
    • Thinking a prior sale burned your turn. No downsizer contribution made means no turn burned.

    Tips to get it right

    • Treat it as your last contribution, not your first. One-shot, any age over 55, no balance limits — so use salary sacrifice, carry-forward and bring-forward first, and keep the downsizer in reserve. Do not sell a qualifying home at 56 “to use it” if a bigger sale may come at 70.
    • Time the sale around your 55th birthday. Age is tested at contribution: sell at 54, settle, turn 55, contribute inside the window — that works. Contribute at 54 — that does not.
    • Split deliberately across funds inside the 90 days (one form per payment) — some couples use this to equalise balances for transfer-balance-cap planning.
    • Match the 90 days to your cash flow. The money must come from the proceeds. If they are tied up paying out a mortgage or bridging into the next purchase, make sure $300,000 per person is liquid inside the window.
    • Kill the FHSS myth. A downsizer contribution cannot be released later under the First Home Super Saver scheme. Anyone saying otherwise is confusing it with ordinary voluntary contributions.
    • Get advice near $3 million. Division 296, the transfer balance cap and estate planning interact in ways a checklist cannot resolve.

    Frequently asked questions

    Do we have to buy a smaller home to qualify?

    No. There is no requirement to buy a smaller, cheaper or any home. The ATO only cares that you sold an eligible home and met the conditions.

    Only my spouse is on the title. Can I still contribute?

    Yes, if you meet the other rules — 55+, the 10-year ownership satisfied through your spouse, main-residence exemption applying, 90-day timing, the form, and no prior downsizer contribution. Each of you can put up to $300,000 into your own accounts.

    We sold for $480,000. Can we each still contribute $300,000?

    No. Combined contributions cannot exceed total sale proceeds — $480,000 between you. Split it $300,000/$180,000, $240,000/$240,000, or any mix up to $300,000 each.

    Settlement keeps getting delayed and 90 days will pass. What now?

    Contact the ATO as soon as possible — ideally before the 90 days expire — and request an extension, explaining the circumstances. Extensions are granted for genuine delays. Never contribute late without an approved extension.

    I put in $200,000 from last year’s sale. Can I add $100,000 now?

    Not from a later sale, and not once your original window closed. One downsizer opportunity per person, capped at $300,000. Within the original 90 days you could have topped up to $300,000 across several payments — which is why you plan the full amount before the first dollar moves.

    Can I claim a tax deduction, and will it affect my Age Pension?

    No deduction is available — it is after-tax money, untaxed on entry instead. And yes, it can affect the Age Pension: the family home is assets-test exempt, but the proceeds and your super balance generally are not, and deemed income can affect the income test. Talk to Services Australia’s Financial Information Service before you sell if the pension matters to you.

    The bottom line

    The downsizer contribution is the most generous single contribution the super system offers: $300,000 per person, no caps, no work test, no balance test, no entry tax, both spouses from one sale. In 2026-27 it pairs with higher general caps and the new Division 296 regime — more valuable than ever, and slightly more dangerous near $3 million.

    The mechanics are simple but unforgiving: eligible home, 55+, form with the fund, money in within 90 days of settlement, once per lifetime. Get those five right and a home sale becomes the biggest single boost your super ever receives. Start with the ATO’s official downsizer super contributions page and take it from there.

  • Super Co-Contribution Australia 2026-27: The Free $500 Guide

    Super Co-Contribution Australia 2026-27: The Free $500 Guide

    The short answer

    If you earn under $64,293 in 2026-27 and put after-tax money into your super, the government adds 50 cents for every dollar you contribute — up to $500 a year. Earn $49,293 or less, contribute $1,000, and you collect the full $500. There is no application form: the ATO works it out from your tax return and pays it straight into your fund. That is a 50% instant return on your money, which no salary-sacrifice arrangement can match at low incomes.

    How the super co-contribution works

    The scheme is simple at its core. You make a personal contribution to your super from after-tax income — money you have already paid tax on — and the government matches part of it. Two conditions decide how much free money you get:

    • How much you contribute. The government pays 50 cents for every dollar of your eligible personal contribution, up to a maximum payment of $500. So contributing $1,000 is the most you ever need to contribute to unlock the full match.
    • How much you earn. If your total income is at or below the lower threshold, you qualify for the full $500. Between the two thresholds, the maximum entitlement shrinks by 3.333 cents for every dollar you earn over the lower threshold. At or above the higher threshold, the entitlement is nil.

    The actual payment is the lesser of those two numbers — 50% of what you contributed, capped by your income-based maximum. Once your tax return is lodged and assessed, the ATO pays it automatically into your super account. The payment itself is not taxed, is not declared as income, and stays preserved in super.

    One critical rule sits underneath all of this: the contribution must be one you do not claim a tax deduction for. Claim a deduction and the match on that money is gone — it becomes an ordinary concessional contribution instead.

    2026-27 thresholds and matching rates

    These are the official ATO figures for the year ending 30 June 2027. Watch out: several popular guides still display 2025-26’s $47,488/$62,488 pair under a 2026-27 heading — the table below is current.

    Financial year Maximum co-contribution Matching rate Lower income threshold Higher income threshold
    2026-27 $500 50c per $1 $49,293 $64,293
    2025-26 $500 50c per $1 $47,488 $62,488

    The lower threshold is indexed each year in line with average weekly ordinary time earnings; the higher threshold always sits exactly $15,000 above it. To see the pattern at a glance, here is what the maximum entitlement looks like at different income levels for 2026-27, assuming you contribute at least $1,000:

    Your total income Maximum co-contribution
    $49,293 or less $500 (full match)
    $52,293 $400
    $55,293 $300
    $58,293 $200
    $61,293 $100
    $64,293 or more $0 (not eligible)

    Handy rule of thumb inside the phase-out zone: you never need to contribute more than twice your maximum entitlement. At $58,293 your entitlement caps at $200, so contributing $400 gets you every dollar of it. If you want to model the exact numbers for your own salary, our super contributions tool runs the 2026-27 figures.

    Eligibility checklist: all seven tests

    You must pass every one of these for the ATO to pay you:

    1. Made a personal after-tax contribution. At least one contribution to a complying super fund during 2026-27, with no tax deduction claimed on it. Salary-sacrifice amounts do not count.
    2. Total income below $64,293. “Total income” is wider than taxable income (see the trap section below) — it includes reportable fringe benefits and reportable employer super contributions.
    3. The 10% employment test. At least 10% of your total income must come from employment-related activities, running a business, or a combination. This is how self-employed people qualify — and also why a 17-year-old working a part-time job can receive the payment. There is no minimum age; the only age rule is being under 71 at the end of the financial year.
    4. Lodged a tax return. No return, no assessment, no payment. The ATO can only calculate your entitlement once your return is processed.
    5. TFN with your fund. Your tax file number must be on record with the super fund. A missing TFN is one of the most common reasons payments never arrive.
    6. Balance and cap tests. Your total super balance must have been below the general transfer balance cap ($2.1 million for 2026-27) on 30 June 2026, and you must not have exceeded the $130,000 non-concessional contributions cap in 2026-27.
    7. Residency. You must not have held a temporary resident visa at any time during the year (New Zealand citizens and certain prescribed-visa holders are excepted).

    One payment per person per year — if you contribute to two funds, the ATO aggregates the contributions and pays a single entitlement of up to $500.

    Worked examples with real 2026-27 figures

    Example 1: Mia earns $40,000 and contributes $1,000

    Mia’s total income of $40,000 sits below the $49,293 lower threshold, so her maximum entitlement is the full $500. She contributes $1,000 of after-tax money to her super and claims no deduction. The government matches 50% of her contribution: 50c × $1,000 = $500, which is within her $500 maximum. Result: $1,500 lands in Mia’s super for $1,000 of her own money — a 50% instant, risk-free return.

    Example 2: Jack earns $55,000 and contributes $1,000

    Jack is inside the phase-out zone. His income exceeds $49,293 by $5,707, so his maximum entitlement is reduced by $5,707 × 3.333c ≈ $190, giving him an entitlement of roughly $310. He contributes $1,000; 50% of that is $500, but his payment is capped at his $310 entitlement. Had he contributed only $620 he would still have collected the full $310 — the rest earns no match. This “twice your entitlement” rule stops you over-contributing for nothing.

    Example 3: Sofia earns $62,000 and contributes $1,000

    Sofia is near the top of the phase-out zone. Her income exceeds $49,293 by $12,707, so her entitlement is reduced by $12,707 × 3.333c ≈ $424, leaving roughly $76. She contributes $1,000 and receives $76 — a contribution of just $152 would have secured the whole $76. Earn $64,293 or more and the entitlement hits zero.

    Co-contribution vs salary sacrifice vs spouse contribution: the $45,000 decision

    Suppose you earn $45,000 and have $1,000 to direct toward super. Which move wins in 2026-27? (At $45,000 your marginal income-tax rate is 15%, plus the 2% Medicare levy — 17% all up.)

    Strategy What happens to your $1,000 Government help Net outcome
    After-tax contribution (co-contribution) $1,000 into your super $500 match $1,500 in your super
    Salary sacrifice $1,000 pre-tax into super, taxed 15% inside the fund $170 tax saving $850 in super, costing you $830 of take-home — a net gain of about $20
    Spouse contribution $1,000 into your partner’s super (if they earn under $37,000) 18% tax offset = $180 off your tax bill Partner’s super +$1,000, your tax −$180 — but your super gets nothing

    The verdict for a $45,000 earner is not close: the co-contribution turns $1,000 into $1,500, while salary sacrifice nets about $20 once the 15% contributions tax is accounted for. The spouse-contribution offset is a different animal: it rewards you for topping up a low-income partner’s super, with up to $540 available on a $3,000 contribution — and the receiving spouse could also make their own $1,000 personal contribution and collect their own $500 co-contribution.

    For the salary-sacrifice mechanics in detail, see our superannuation tax and salary sacrifice guide, and check how the contributions sit against the annual limits in our super contribution caps guide.

    The “total income” trap: why some people miss out entirely

    This is the single most misunderstood part of the scheme. Your co-contribution eligibility is not tested on your taxable income — it is tested on a wider measure called total income, which includes:

    • your assessable income before deductions,
    • reportable fringe benefits (a novated lease car benefit, for example), and
    • reportable employer super contributions (which includes salary-sacrifice amounts).

    Three traps fall out of this definition:

    Trap 1: Claiming a deduction does not help. Because assessable income is measured before deductions, claiming a $1,000 tax deduction for your personal contribution does nothing for your co-contribution eligibility — but it does disqualify the contribution from the match. You lose the $500 and gain nothing. If you want the match, do not claim. Our tax deductions checklist explains which contributions you can claim for.

    Trap 2: Salary sacrifice can push you over the cliff. Salary-sacrifice contributions count as reportable employer super contributions, so they increase your total income for this test. On a $58,000 salary with no sacrifice, total income is $58,000 and the entitlement is roughly $210. Salary-sacrifice $4,000 and total income becomes $62,000 — the entitlement collapses to about $76. The sacrifice earns no match itself. For co-contribution purposes, salary sacrifice is all cost and no benefit.

    Trap 3: Fringe benefits and bonuses. A $5,000 Christmas bonus or a reportable fringe benefit from salary packaging can silently carry total income over $64,293 and wipe the entitlement to zero. If you are anywhere near the higher threshold, estimate your total income — not just your salary — before counting on the payment. You can sanity-check your marginal rate on our income tax tool alongside the 2026-27 tax rates guide.

    Can you get the co-contribution AND the LISTO payment?

    Yes — and low earners should know these are two separate schemes. The Low Income Superannuation Tax Offset (LISTO) refunds the 15% contributions tax paid on your concessional contributions (like your employer’s super guarantee) if your income is $37,000 or less, up to $500 a year. The co-contribution rewards your after-tax contributions. Meet both sets of rules and you collect both.

    Worked example: Alex earns $35,000. His employer’s 12% super guarantee is $4,200, on which the fund pays 15% tax ($630). LISTO refunds $500 of that (the maximum) back into his fund automatically. Alex also contributes $1,000 after tax with no deduction claimed — his income is below $49,293, so he collects the full $500 co-contribution too. Total government money added to Alex’s super: $1,000. (The government has announced the LISTO threshold will rise to $45,000 with an $810 maximum from 1 July 2027 — announced, not yet law, so it does not apply to 2026-27.)

    Common mistakes that kill the payment

    • Claiming a tax deduction on the same contribution. This is the number-one self-inflicted error.
    • No TFN on file with the fund. Check your fund’s app or member portal — a missing TFN is one of the most common reasons payments never arrive.
    • Assuming salary sacrifice counts. It does not, and it inflates your total income as well.
    • Using taxable income instead of total income — then discovering a fringe benefit or bonus pushed you over $64,293.
    • Contributing after 30 June. The fund must receive the money by 30 June 2027. A BPAY made on 30 June that lands in July can miss the cut-off — contribute a week early.
    • Expecting the money in your bank account. The payment goes into your super and stays preserved. It is retirement money, not a refund.
    • Not lodging a tax return. The ATO cannot assess an entitlement it never sees.
    • Ignoring the $130,000 non-concessional cap. The $500 government payment doesn’t count toward it — but your $1,000 does, and for big contributors it can trigger the bring-forward rule.
    • Changing funds without updating details. If the fund that reported your contributions can no longer accept the payment, the ATO will contact you for an alternative fund’s details — respond, or the money sits in limbo.

    Tips to get the full $500

    • Check your TFN is with your fund now, not after 30 June. It takes two minutes in most fund apps.
    • In the phase-out zone, contribute exactly twice your entitlement. At $55,000 that is about $620; at $60,000 (entitlement ≈ $143) it is about $286. Any more earns no extra match.
    • Keep the contribution and the deduction decision separate. Decide in advance: this $1,000 is for the co-contribution, so no deduction gets claimed on it.
    • Time it before mid-June to dodge EOFY processing delays.
    • Estimate total income first if you have fringe benefits or bonuses — a rough calc now beats a surprise “not eligible” later.
    • Couples: double-dip legally. Each partner can earn their own $500 on their own contributions. A household where both partners earn under $49,293 and each contributes $1,000 collects $1,000 of government money.

    Frequently asked questions

    Do I need to apply for the co-contribution?

    No. There is no form and no application. Make an eligible after-tax contribution, lodge your tax return, and the ATO calculates and pays your entitlement automatically — provided your fund holds your TFN.

    When will the payment actually arrive?

    After your tax return for the year is assessed. In practice most payments land between November and January of the following financial year. If the ATO takes more than 60 days from receiving all the required information, it must add interest to your payment to compensate for the delay.

    I earn $63,000 — is it even worth bothering?

    Probably yes, because the contribution needed is tiny. At $63,000 your entitlement is roughly $43 (income exceeds $49,293 by $13,707; $13,707 × 3.333c ≈ $457 reduction). Contribute about $87 after tax and you collect the full $43 — still close to a 50% return.

    Can salary sacrifice and the co-contribution be combined?

    Technically yes — nothing stops you doing both in the same year — but salary sacrifice never earns the match and it increases your total income, which can shrink the match you get on your after-tax contributions. Run the numbers before combining them.

    I’m 70. Am I too old?

    Not necessarily. The rule is that you must be under 71 at the end of the financial year (30 June 2027). Turn 71 during the year and you still qualify for that year.

    What if I didn’t receive a payment I think I’m owed?

    First re-check every eligibility test — total income definition, the 10% employment test, the deduction rule, and your TFN. If everything holds, phone the ATO on 13 10 20 or write to request a review of the decision. Keep records of your contribution receipts and your tax return.

    The bottom line

    The super co-contribution is the closest thing Australian tax law offers to free money: a 50% instant return for putting $1,000 of after-tax savings into your super. The 2026-27 thresholds are $49,293 for the full $500 and $64,293 as the cut-off, the payment is automatic, and the most common ways people miss out — claiming a deduction, a missing TFN, or salary sacrifice inflating their total income — are all avoidable. Contribute before 30 June 2027, lodge your return, and let the ATO do the rest.

    General information only — not personal financial advice. Figures are the ATO’s 2026-27 rates and thresholds; confirm your situation with the ATO or a registered tax agent. ATO references: the super co-contribution page and the government contributions thresholds table.

  • Carry-Forward Super Contributions Australia 2026-27: Catch-Up Caps & Worked Examples

    Carry-Forward Super Contributions Australia 2026-27: Catch-Up Caps & Worked Examples

    If you haven’t maxed out your super contributions in recent years, the tax system owes you a second chance — literally. Carry-forward (catch-up) concessional contributions let you mop up unused super caps from the last five financial years and claim them as one big tax deduction in 2026-27. For someone sitting on $70,000 of unused cap space, that’s a deduction worth up to $32,900 off this year’s tax bill.

    But there’s a catch hiding in the fine print: unused cap from 2021-22 expires on 30 June 2027. If you don’t use it this financial year, it vanishes. Here’s how the rules work, how to check your balance, and the traps that catch people out.

    How carry-forward contributions work

    Since 1 July 2018, your concessional contributions cap hasn’t been a hard annual ceiling. Under section 291-20 of the tax law, any cap you didn’t use in the previous five financial years gets added to your current-year cap automatically. The ATO tracks it from what your funds report — there’s no form to lodge and no election to make.

    For 2026-27, the five years that count are:

    • 2021-22: cap was $27,500
    • 2022-23: cap was $27,500
    • 2023-24: cap was $27,500
    • 2024-25: cap was $30,000
    • 2025-26: cap was $30,000
    • 2026-27 (this year): cap is $32,500

    Your boosted cap for 2026-27 is $32,500 plus whatever you didn’t use across those five years. In the absolute best case — zero concessional contributions for five straight years — that’s $27,500 × 3 + $30,000 × 2 + $32,500 = $175,000 of concessional contributions in a single year. Most people will have a smaller number because employer super guarantee used up part of the cap along the way.

    One rule matters more than any other: your total super balance across every account you hold must have been under $500,000 at 30 June 2026. Not $500,000 or less — strictly under. A balance of exactly $500,000 fails the test. The threshold isn’t indexed either, so it stays $500,000 every year.

    The expiry calendar: 2021-22 amounts die this year

    Unused cap doesn’t wait around forever. Each year’s unused amount expires five years after it arose, and the oldest amounts are always used first. That means right now, in 2026-27, the clock is ticking on one specific cohort:

    Unused cap from Cap that year Last financial year you can use it
    2021-22 $27,500 2026-27 — expires 30 June 2027
    2022-23 $27,500 2027-28
    2023-24 $27,500 2028-29
    2024-25 $30,000 2029-30
    2025-26 $30,000 2030-31

    Unused amounts from 2020-21 already expired on 30 June 2026 — they’re gone, no extensions, no appeals. If your myGov carry-forward figure includes 2021-22 amounts, this is the year to use them or lose them. Nobody else’s guide seems to put this deadline front and centre, which is exactly why so much unused cap quietly evaporates every 30 June.

    Step-by-step: using your carry-forward cap in 2026-27

    Step 1 — Check your actual balance on myGov

    Don’t guess. Log in to myGov, open the ATO service, go to Super → Information → Carry-forward concessional contributions. It shows your unused amounts and confirms whether you pass the $500,000 test. A few timing quirks to know:

    • Figures for the current financial year may not appear for the first few months.
    • If you have an SMSF, last year’s figure won’t be right until your SMSF annual return is processed.
    • Defined-benefit fund members: prior-year contribution info may not reach the ATO until 31 October.

    Step 2 — Work out your real room

    Your boosted cap is $32,500 plus your unused amounts. But your employer contributions count too — the 12% super guarantee (now paid with each pay cycle under payday super) and any salary sacrifice both eat into the same cap. So:

    Room left = ($32,500 + unused amounts) − (employer SG + salary sacrifice already paid or expected this year)

    This is where most people trip up. On a $150,000 salary, 12% SG alone is $18,000 — more than half the base cap gone before you’ve done anything.

    Step 3 — Make the contribution

    You can use either salary sacrifice or a personal deductible contribution. For most people making a catch-up, a personal contribution is simpler — one lump sum from your bank account to your fund. Critical timing point: your fund must RECEIVE the money by 30 June. Clicking “pay” on 30 June with a bank transfer that clears on 1 July means the contribution counts for next year, not this one. Most funds suggest allowing at least a week.

    Step 4 — Lodge your notice of intent

    If you made a personal contribution and want the tax deduction, you must lodge a Notice of Intent to Claim a Tax Deduction with your fund — and the fund must acknowledge it — before you lodge your tax return. This cannot be done retrospectively. If you have more than one fund and contributed to both, you need a separate notice for each fund. And if you roll over or withdraw the contribution before the notice is acknowledged, the deduction is lost entirely.

    Worked example 1: Sophie’s $70,000 catch-up

    Sophie earns $180,000 in 2026-27. Her total super balance was $340,000 at 30 June 2026, so she passes the $500,000 test. Her myGov shows $70,000 of unused cap from 2021-22 to 2025-26.

    Her employer pays $12,000 in super guarantee this year. Her boosted cap is $32,500 + $70,000 = $102,500, so she has $90,500 of room. She makes a $70,000 personal deductible contribution and lodges her notice of intent.

    • Tax saved on her income: $70,000 × 39% (37% bracket + 2% Medicare levy) = $27,300
    • Tax paid inside super: $70,000 × 15% = $10,500
    • Net tax saving: $16,800 — plus $70,000 more compounding in super

    Division 293 check: her income for Division 293 purposes comes in around $192,000 (taxable income after the deduction plus total concessional contributions) — comfortably under the $250,000 threshold, so no extra 15% applies. That’s a clean $16,800 win.

    Worked example 2: Daniel’s redundancy year (with the Division 293 sting)

    Daniel is made redundant in 2026-27 and his taxable income lands at $280,000. His balance was $410,000 at 30 June 2026 and he has $60,000 of unused cap. Between jobs, he has no employer contributions this year.

    He makes a $60,000 personal deductible contribution. His taxable income drops to $220,000.

    • Income tax saved: $60,000 × 47% (45% bracket + 2% Medicare) = $28,200
    • Contributions tax in super: 15% × $60,000 = $9,000
    • Division 293: his income for Division 293 purposes is $220,000 + $60,000 = $280,000 — $30,000 over the $250,000 threshold. Extra 15% on the $30,000 excess = $4,500
    • Net saving: $28,200 − $9,000 − $4,500 = $14,700

    Still a $14,700 win on top of $60,000 extra in super — but notice how Division 293 quietly took $4,500 off the headline saving. High earners doing big catch-ups should always model this before contributing, not after.

    7 common mistakes that cost real money

    1. The 30 June illusion. The contribution counts when your fund receives it, not when you send it. BPAY and bank transfers can take days. Aim for mid-June at the latest.

    2. The notice-of-intent trap. Personal contribution, no notice lodged (or lodged after your tax return, or never acknowledged by the fund) = no deduction, and the money still counts against your cap. With multiple funds, it’s one notice per fund.

    3. Guessing instead of checking myGov. Your employer’s SG and any salary sacrifice already used part of your space. The ATO’s figure is the source of truth — your mental arithmetic isn’t.

    4. Misreading the $500,000 test. It’s all accounts combined, measured at the previous 30 June, strictly under $500,000, never indexed. But failing one year isn’t fatal — it’s re-tested every 30 June, so a market dip can reopen the window before your oldest unused years expire.

    5. Ignoring Division 293. As Daniel’s example shows, a big catch-up in a high-income year can push your Division 293 income over $250,000 and trigger an extra 15%. Still usually worth it — just know the real number.

    6. Trying to use a partner’s unused cap. Carry-forward is strictly per-member. You cannot transfer, gift or share unused cap with a spouse, no matter how much sense it would make.

    7. Blowing past the boosted cap. If you overshoot, the excess is added to your assessable income and taxed at your marginal rate (with a 15% offset for the contributions tax already paid). You can elect to release up to 85% of the excess, but anything left in the fund also counts toward your non-concessional cap. Measure twice, contribute once.

    When carry-forward pays off most

    The strategy shines in lumpy-income years — the exact years when a big deduction is worth the most:

    • A property or share sale: a large capital gain in 2026-27 pairs beautifully with a catch-up contribution to pull taxable income back down.
    • Redundancy or termination payouts: the payout pushes you into a higher bracket for one year only — the perfect year to deploy unused cap.
    • Bonus or business profit spike: contractors and business owners with volatile income can bank unused cap in lean years and spend it in bumper ones.
    • Before the 2021-22 amounts expire: if any of your unused cap dates from 2021-22, 30 June 2027 is a hard deadline regardless of your income year.

    One more coordination point: if you’re already salary sacrificing, factor it into your room calculation first. And if you’re 67 to 74, you generally need to meet the work test (40 hours in a 30-day period) to contribute at all — though a one-off work-test exemption exists if your balance was under $300,000 at the previous 30 June.

    FAQ

    How do I check my carry-forward balance?

    Log in to myGov → ATO → Super → Information → Carry-forward concessional contributions. It shows your unused amounts by year and whether you meet the $500,000 test. If you have an SMSF, wait until your annual return is processed for an accurate figure.

    Do I need to be employed to use carry-forward contributions?

    No. Anyone eligible can make a personal deductible contribution — employees, the self-employed, and even people not working. If you’re 67 to 74, the work test (or its one-off exemption) applies.

    Can I use my partner’s unused super cap?

    No. Unused concessional cap is personal to each member and cannot be transferred or shared, even with a spouse.

    What happens if I contribute more than my boosted cap?

    The excess is included in your assessable income and taxed at your marginal rate, with a 15% tax offset for contributions tax already paid. You can elect to have up to 85% of the excess released from super; any excess left in the fund also counts toward your non-concessional contributions cap.

    Is the $500,000 test a one-off?

    No — it’s tested fresh every 30 June. If your balance is over $500,000 this year, you can’t use carry-forward this year, but you can use it in a later year (before the oldest amounts expire) if your balance drops back under.

    Do salary sacrifice and employer SG use up my unused amounts?

    Yes. Every concessional contribution — SG, salary sacrifice, personal deductible — counts against the same cap. Unused amounts from the oldest year are applied first, which is why the 2021-22 cohort is the one to watch this year.

    The bottom line

    Carry-forward contributions are one of the few genuine “do-overs” in the tax system: five years of unused super cap, claimable as a single deduction. In 2026-27 the maths is unusually generous — a $32,500 base cap, up to $142,500 of historical room, and a 15% contributions tax rate against marginal rates as high as 47%. The two things to get right are the 30 June 2027 expiry of 2021-22 amounts and the notice of intent before you lodge your return. Get those right, check your real figure on myGov, and a catch-up contribution can be the single biggest legal tax saving you make this year. Run your own numbers with our super tax calculator and income tax calculator before you commit.

    Further reading: Super Contribution Caps 2026-27 · Superannuation Tax & Salary Sacrifice · Division 293 Tax Explained · First Home Super Saver Scheme · Division 296: the $3M Super Tax · ATO: Concessional contributions cap

  • SMSF Property Investment Australia 2026-27: Rules & Tax

    SMSF Property Investment Australia 2026-27: Rules & Tax

    If you are thinking about buying property through your self-managed super fund in 2026-27, you need to know one thing before anything else: from 10 August 2026, SMSFs can no longer take out a new loan to buy residential property. The rule that let funds gear into houses and units with a limited recourse borrowing arrangement (LRBA) is gone for new residential deals. Cash purchases are still allowed, commercial property borrowing still works, and every pre-ban loan is grandfathered — but the strategy has fundamentally changed. This guide covers the new rules, verified 2026-27 rates and caps, real costs in dollars, and a full worked example so you can judge whether it still stacks up.

    How SMSF property investment works in 2026-27

    An SMSF is a private super fund where you are both member and trustee (up to 6 members allowed). Because you control the investment decisions, the fund can buy direct property — something industry and retail funds generally don’t offer. The payoff is tax: rental income is taxed at 15% while you’re in accumulation phase, and 0% once the fund is paying you a pension. Capital gains held longer than 12 months get a one-third discount inside super, so the effective CGT rate is 10% in accumulation (0% in pension).

    What changed this year is the borrowing side. The Treasury Laws Amendment (Tax Reform No. 1) Act 2026 received Royal Assent on 26 June 2026, and 45 days later — 10 August 2026 — the ban took effect: no new LRBA may be used to acquire residential property. The trigger is the contract-exchange date, so only contracts signed before 10 August 2026 are protected. Existing LRBAs are fully grandfathered and can even be refinanced. Borrowing to acquire business real property (commercial property used wholly and exclusively in a business) is not affected at all.

    In practical terms, the question has shifted. It used to be “how much can my SMSF borrow?” Now it is two questions: “can my SMSF buy this asset?” (usually yes, with cash) and “can my SMSF borrow to buy it?” (only if it’s business real property). If you want to model the tax side yourself, the super tax calculator on this site lets you compare accumulation-phase and pension-phase outcomes side by side.

    The official numbers: 2026-27 rates, caps and rules

    Every figure below is the verified 2026-27 figure. Note that several popular guides still quote last year’s caps — the concessional cap rose to $32,500 and the non-concessional cap to $130,000 from 1 July 2026.

    Item 2026-27 figure
    Tax on SMSF rental income (accumulation) 15%
    Tax on SMSF rental income (pension phase) 0%
    CGT on assets held 12+ months (accumulation) One-third discount = 10% effective
    CGT in pension phase 0%
    Concessional contributions cap $32,500 per year
    Concessional carry-forward Unused cap rolls forward 5 years if your total super balance was under $500,000 at the prior 30 June
    Non-concessional contributions cap $130,000 per year (bring-forward up to $390,000 over 3 years)
    Super guarantee rate 12%
    Transfer balance cap (pension phase limit) $2.1 million
    Division 293 threshold $250,000 (extra 15% tax on some or all concessional contributions above this)
    Division 296 (from 1 July 2026) Extra 15% tax on earnings attributable to balances over $3m; further 10% over $10m
    In-house asset limit 5% of fund assets
    Non-arm’s-length income (NALI) tax rate 45%
    Maximum SMSF members 6

    The contribution caps matter more than ever, because with residential borrowing gone, the caps are now your deposit engine. Getting a large lump sum into the fund is how you fund a cash purchase: concessional contributions of $32,500 a year, unused concessional cap carried forward for up to five years, non-concessional contributions of $130,000 a year (or $390,000 in one hit under the bring-forward rule), and downsizer contributions of $300,000 per person if you’re 55 or older and selling a home you’ve owned for 10+ years. For the full breakdown, see our 2026-27 contribution caps guide. If you’re a high earner, watch the Division 293 threshold too — explained in our Division 293 guide.

    Step-by-step: buying property through your SMSF

    1. Set up (or review) the SMSF. Trust deed, trustee structure (corporate trustee is strongly recommended — roughly $1,000–$1,500 for ASIC registration), TFN/ABN, bank account, and an investment strategy that explicitly permits direct property. Establishment typically costs $2,000–$4,000 all-in. Allow 4–8 weeks before you start making offers.
    2. Get the balance right. Don’t start a property SMSF with less than $300,000: for a cash-funded residential purchase you need the full price plus purchase costs plus a liquidity buffer (6–12 months of expenses in cash or liquid assets — your auditor will check this against your investment strategy).
    3. Decide residential or commercial. Residential = cash only (new loans banned). Commercial business real property = cash or LRBA. If borrowing for commercial, the property must be held in a separate bare trust, it must be a single acquirable asset per loan, the fund’s investment strategy must permit borrowing, and the lender’s recourse is limited to that property alone.
    4. Line up finance early (commercial LRBA only). Expect a 30–40% deposit, fund balance of $300,000+, and proof the rent services the debt. SMSF loan rates in 2026 sit roughly around 6.6%–7.5% — higher than standard investment loans — and LVRs are stricter (60–70% for commercial).
    5. Buy at arm’s length. The fund cannot buy residential property from you, your family, or any related party — full stop. It cannot rent residential property to related parties either, and you can never live in it. Commercial property is the one exception: it can be acquired from and leased to a related party, but only if it meets the “business real property” definition, the price is genuine market value, and the lease is on documented commercial terms.
    6. Keep it compliant, every year. Annual independent audit, tax return, market-value valuations of the property, minutes for trustee decisions, and insurance that actually covers a vacant or damaged property. Ongoing admin runs $3,500–$7,000 a year (accounting $2,500–$5,000, audit $800–$1,500, plus ASIC and ATO levies).

    Worked example: a $600,000 unit, cash-funded, vs your personal name

    Meet Priya, 48, on a $190,000 salary. Her SMSF holds $700,000. She buys a $600,000 two-bedroom unit as an investment. Because new residential LRBAs are banned, the fund pays cash.

    What the fund needs on day one:

    • Purchase price: $600,000
    • Stamp duty and purchase costs: ~$25,000
    • Liquidity buffer left in the fund: ~$35,000
    • Total committed: ~$660,000 — her $700,000 fund just covers it.

    Annual rental position. The unit rents for $590 a week — about $30,680 a year, a 5.1% gross yield (check your own numbers with a rental yield calculator). Annual expenses: agent fees $2,150, rates $2,200, insurance $900, maintenance $1,500 — roughly $6,750. Net rent: $23,930.

    The tax comparison. Inside the SMSF in accumulation phase, that $23,930 is taxed at 15% = $3,590. In Priya’s personal name, the same net rent is taxed at her marginal rate of 47% (45% plus 2% Medicare levy) = $11,247. Annual saving: about $7,660. Run the personal-side numbers on an income tax calculator to see your own marginal rate.

    The sale, 12 years later. Priya sells for $980,000. Capital gain: $380,000. Inside the SMSF (held over 12 months), the one-third CGT discount leaves $253,333 taxable at 15% = $38,000 tax (an effective 10%). In her personal name, the 50% CGT discount leaves $190,000 taxable at 47% = $89,300 tax. Model the difference with a CGT calculator. CGT saving: about $51,300.

    Two honest caveats. First, the fund’s $3,500–$7,000 annual admin bill is roughly $60,000 of drag over 12 years — which is why small balances don’t work. Second, in her personal name Priya could have negatively geared: a $480,000 loan at ~6.2% costs ~$29,760 a year in interest, creating a deductible loss against her salary. Inside super, losses are trapped in the fund and can’t offset your personal income. For how negative gearing works outside super, see our negative gearing guide.

    Where borrowing still works: the commercial path. Priya’s brother runs a plumbing business and his SMSF buys the $800,000 warehouse the business operates from, using an LRBA: 65% LVR means a $520,000 loan and $280,000 of fund cash plus costs. The business leases it back at a documented market rent of $65,000 a year. Loan interest at ~7% is about $36,400, and the net rent is taxed at 15%. The trap to avoid: if the rent is a dollar below market or the terms aren’t arm’s length, the income can be hit with non-arm’s-length income tax at 45%. Get an independent rental appraisal and a proper commercial lease, every time.

    Common mistakes that cost trustees thousands

    • “Just one weekend” in the property. Members and related parties can never occupy an SMSF property — not for a night, not for storage, not for a working holiday. Any personal use breaches the sole purpose test and can see the fund made non-complying, with the whole balance taxed at marginal rates.
    • Renting to family at a “good” rent. Residential property cannot be leased to related parties at any price. Commercial property can, but only at full market rent with documentation — otherwise NALI at 45%.
    • Buying residential from yourself or family. Prohibited, no exceptions. Only business real property (and listed securities) can be acquired from a related party, and only at genuine market value.
    • Assuming a builder’s “single-contract” package beats the ban. Since 10 August 2026, no new loan structure — however cleverly packaged — can be used to gear into residential property. Turnkey residential deals marketed as “LRBA-compliant” are selling a structure the law no longer permits.
    • Improving the property with borrowed money. Under an LRBA, borrowed funds can maintain or repair the asset but cannot improve it — and an improvement can change the character of the “single acquirable asset”, breaching the borrowing rules. Fund improvements from the fund’s own cash, with advice.
    • Co-owning with yourself and getting the split wrong. You and your SMSF can co-own a property as tenants in common, but every dollar — rent, rates, insurance, repairs — must be split exactly in proportion to ownership, and the fund’s share must land in the fund’s bank account. If you personally cover an expense the fund should have paid, the fund’s income can be taxed at 45% as non-arm’s-length expenditure. A related unit trust can work, but only if it meets strict conditions (no borrowing, no charges, no business) or the units count toward the 5% in-house asset cap.
    • Ignoring Division 296 when the fund is all property. From 1 July 2026, if your total super balance exceeds $3 million, an extra 15% tax applies to the earnings attributable to the balance above $3 million (30% effective; 40% above $10 million). The ATO assesses you personally — and if your wealth is locked in property, finding the cash to pay (or arranging a release from the fund within 60 days) is genuinely hard. SMSFs get a one-time CGT cost-base reset election, due by the lodgement date of the 2026-27 return — worth modelling before the deadline passes.

    Tips to make it work

    • Use the caps as your deposit engine. With residential borrowing gone, contributions are how you build a purchase war chest: $32,500 concessional a year, up to five years of unused concessional cap if your balance is under $500,000, $130,000 non-concessional a year (or $390,000 under the bring-forward rule), and $300,000 each as a downsizer contribution from age 55.
    • Time the pension phase. The real magic is 0% tax on rent and gains in pension phase. Buying in your late 40s/early 50s and holding into pension phase maximises the compounding of the tax saving — but watch the $2.1 million transfer balance cap on how much can sit in the tax-free pension.
    • Keep the paperwork boring. Market appraisals, arm’s-length leases, trustee minutes for every decision, valuations at 30 June. Auditors and the ATO love boring.
    • Get advice before you sign anything. SMSF property is one of the highest-penalty areas in the tax system. A few thousand dollars of specialist advice is cheap compared with a non-complying fund determination. This article is general information, not personal advice.

    Frequently asked questions

    Can I live in a property owned by my SMSF — even just occasionally?

    No. Members, relatives and related entities cannot occupy an SMSF property at any time, for any reason. It breaches the sole purpose test, and the penalties range from administrative fines per trustee to the fund being made non-complying — which means the entire balance can be taxed at your marginal rate.

    Can my SMSF still borrow to buy property after the August 2026 changes?

    For residential property: no new LRBAs from 10 August 2026 — purchases must be cash-funded. Existing residential LRBAs are grandfathered and can be refinanced. For commercial property that qualifies as business real property: yes, LRBAs are still fully available, with the usual bare-trust and single-asset rules.

    How much super do I need to buy property in an SMSF?

    A $600,000 residential property needs roughly $660,000 in the fund once you add purchase costs and keep a liquidity buffer. A balance under $300,000 rarely justifies an SMSF at all, because the $3,500–$7,000 annual admin cost eats too much of the return.

    Can my SMSF buy my business premises from me?

    Yes — this is the main related-party exception. The property must be “business real property” (used wholly and exclusively in a business), sold at genuine market value with an independent valuation, and any lease-back must be on documented arm’s-length commercial terms. Get the rent or terms wrong and the income can be taxed at 45% as non-arm’s-length income.

    Can my SMSF and I co-own a property together?

    Yes, as tenants in common, but the rules are strict: every item of income and expense must be split exactly in proportion to ownership, and the fund’s share must go to the fund’s own account. Sloppy splitting can trigger 45% tax on the fund’s income. Get specialist advice before attempting it.

    What happens to my SMSF property when I retire?

    Once the fund pays you a pension (tax-free status typically from 60), rental income and capital gains on the property become tax-free up to the $2.1 million transfer balance cap. But if your total super balance is over $3 million, Division 296 adds extra tax on earnings above that threshold from 2026-27 — plan for how you’d pay it when the asset is illiquid property.

    SMSF property investment in 2026-27 is narrower than it used to be, but the tax maths for the right buyer is still compelling: 15% on rent instead of up to 47%, an effective 10% CGT rate instead of up to 23.5%, and 0% in pension phase. The residential borrowing ban just means the strategy now rewards patience — building the balance through contributions, buying with cash, and holding into retirement. Run your own numbers first, keep every document, and get advice before you commit.

  • Super Death Benefits Tax Australia 2026-27: Rules & Examples

    Super Death Benefits Tax Australia 2026-27: Rules & Examples

    Quick answer

    Australia has no inheritance tax — but your super can still be taxed when it passes to your family. If your super goes to a death benefits dependant (your spouse, a child under 18, or someone financially dependent on you), it is paid out completely tax-free. If it goes to a non-dependant — most commonly an independent adult child — the taxable part is taxed at 17% (15% tax plus the 2% Medicare levy), or 32% on any untaxed element. On a $500,000 balance that is mostly taxable component, the difference between “spouse” and “adult child” as the recipient is more than $70,000 in tax. This guide explains who counts as a dependant, how the tax is actually calculated, the recontribution strategy that can legally cut the bill, and the traps — expired nominations, insurance payouts, and a long-dead tax break people still quote — that cost families money every year.

    Why super is taxed differently from everything else you leave behind

    When you die, your house, shares and bank accounts become part of your estate and your will decides where they go. Superannuation does not work that way. Your super sits in a trust run by your fund’s trustee, and it only leaves the fund when the trustee pays a death benefit — to a nominated dependant, to your estate, or, with no valid nomination, to whoever the trustee decides should get it. Your will has no automatic say over it.

    The tax logic is a clawback. Over your working life your super enjoyed concessions: employer contributions taxed at 15% going in, fund earnings at 15% instead of your marginal rate. Paid to someone genuinely depending on you, those concessions are left alone — tax-free. Paid to an independent adult, the government recovers part of them. Remember this and every rule below follows: dependant = tax-free, non-dependant = clawback.

    Every balance is split into two components. The tax-free component (mostly after-tax contributions from your own pocket) always passes through tax-free, whoever receives it. The taxable component (employer contributions, salary sacrifice, deductible contributions, and all earnings) is where the tax bites. After a career of compulsory employer contributions, most balances are dominated by the taxable component — which is why the 17% figure stings so many families.

    Who counts as a dependant? (Two definitions that trip people up)

    There are two different definitions of “dependant” in play, and they do different jobs:

    Definition Who qualifies What it controls
    SIS dependant (super law) Spouse or de facto partner; any child (any age); a person financially dependent on you; a person in an interdependency relationship with you; your legal personal representative (your estate) Who your fund is allowed to pay the benefit to
    Tax dependant (tax law) Spouse or de facto partner; a child under 18; a person financially dependent on you; a person in an interdependency relationship with you Who gets the benefit tax-free

    The gap between the two rows is where the tax lives. Your 30-year-old daughter is a perfectly valid SIS dependant — your fund can pay her directly — but she is not a tax dependant unless she is financially dependent on you. So the payment is legal, and taxed.

    A nomination can also be invalid without you realising. Only SIS dependants and your estate can be nominated — James, 28, nominating his two independent adult brothers is invalid, and the trustee will use its own discretion instead. Nominating your estate and directing it through your will is the safe catch-all for non-dependants.

    Financial dependency is the grey zone: an adult child living at home rent-free while studying, or a parent you substantially support, can qualify — but it is a question of fact and the fund will ask for evidence. Do not assume it.

    The tax rates: lump sums

    Almost all death benefits are paid as lump sums, and the rates are set by the ATO’s tax tables — they do not depend on anyone’s age or income:

    Recipient Tax-free component Taxable component — taxed element Taxable component — untaxed element
    Tax dependant (spouse, under-18 child, financial dependant) Tax-free Tax-free Tax-free
    Non-dependant (independent adult child, sibling, friend) Tax-free 15% + 2% Medicare = 17% 30% + 2% Medicare = 32%
    Deceased estate (paid to the executor first) Tax-free No tax withheld by the fund; taxed when distributed to the beneficiary

    Two things to notice. First, the taxed element is what almost everyone has: in an ordinary taxed fund (industry, retail, most SMSFs), contributions and earnings were already taxed at 15% inside the fund, so the non-dependant rate is 17%. The untaxed element mostly appears in older public-sector defined benefit schemes — and, per the trap below, in life insurance payouts held inside super. Your annual member statement breaks the components down.

    Second, the fund withholds the tax before paying a non-dependant: 17% or 32% comes off the top and goes to the ATO, like PAYG on wages. The recipient reports the benefit in their tax return and the withheld amount is credited against tax payable.

    Worked example: the $500,000 adult-child bill

    Priya dies at 71 with $500,000 in super. Her statement shows a tax-free component of $75,000 (15%) and a taxable component of $425,000 (85%) — a typical split after a career of employer contributions. She leaves it to her two adult children, Maya and Arjun, equally and directly. Neither is financially dependent on her.

    Each child receives $250,000, made up of $37,500 tax-free component and $212,500 taxable component. The tax-free part is untouched. On the taxable part, the fund withholds 17%: $212,500 × 17% = $36,125 per child. Between them, $72,250 goes to the ATO and $427,750 reaches the family.

    Now change one fact: Priya’s husband is alive and she leaves the same $500,000 to him. He is a tax dependant. The entire $500,000 — tax-free and taxable components alike — is paid with zero tax. That single difference in recipient is worth $72,250. This is why advisers say the most valuable estate-planning decision many couples make is simply making sure the super goes to the surviving spouse first.

    The estate route: 15% instead of 17%

    Here is a nuance almost no general article works through in dollars. If the death benefit is paid to the trustee of the deceased estate rather than directly to the non-dependant, the fund withholds nothing. The estate then distributes the money under the will, and the beneficiary is taxed on the taxable component at that point — at 15% for the taxed element, but without the 2% Medicare levy, because an estate is not a natural person and the levy does not apply to it.

    Run Priya’s numbers through the estate instead. The $425,000 taxable component distributed to Maya and Arjun via the estate is taxed at 15% flat: $425,000 × 15% = $63,750. That is $8,500 less than the $72,250 withheld on direct payment — the same money, the same beneficiaries, different plumbing.

    It is not free money. The benefit sits in the estate while probate runs its course — often months — administration has its own costs, and the will must direct the money to the right people. But for large balances to non-dependants, the 2% saving is worth modelling with an estate lawyer: on a $1 million mostly-taxable balance it is roughly $17,000.

    The recontribution strategy: turning taxable into tax-free while you are alive

    The most powerful legal way to cut the eventual death benefits tax is the recontribution strategy. The idea is simple: once you have met a condition of release (retired after preservation age, or turned 65), you withdraw a lump sum from super — tax-free if you are over 60 — and immediately contribute it back as a non-concessional (after-tax) contribution. Money that goes back in as a non-concessional contribution becomes tax-free component. Repeat over a few years and you steadily convert the taxable component your adult children would be taxed on into tax-free component they receive untouched.

    Two mechanics make or break it. First, the proportioning rule: every withdrawal must come out in the same tax-free/taxable ratio as the account it leaves. You cannot cherry-pick just the taxable part. Second, the contribution caps: in 2026-27 the non-concessional cap is $130,000 a year, or $390,000 under the bring-forward rule, and you need available cap space. Our super contribution caps guide covers the eligibility tests.

    Here it is in dollars. David is 67, retired, with $600,000 in super: $60,000 tax-free component (10%) and $540,000 taxable (90%). If he died tomorrow and it all went to his independent adult son, the tax would be $540,000 × 17% = $91,800.

    Instead, David withdraws $390,000 (within his bring-forward cap) and recontributes it the same week as a non-concessional contribution. The withdrawal, under the proportioning rule, is $39,000 tax-free + $351,000 taxable — and because he is over 60, the withdrawal itself is tax-free to him. The $390,000 that goes back in is 100% tax-free component. His position is now: the original account holds $210,000 ($21,000 tax-free + $189,000 taxable), plus a new account holding $390,000 of pure tax-free component. Total tax-free: $411,000 (68.5%), up from $60,000 (10%).

    If David died the next day, the death benefits tax on the $600,000 would be $189,000 × 17% = $32,130 — a saving of $59,670 from one year’s manoeuvre. One refinement: keep the recontributed money in a separate account (or start a second pension from it) to preserve its 100% tax-free character. Mixed back into the original account, future withdrawals proportion across the blended balance and the benefit dilutes. Standard cautions apply: you need a condition of release, available cap space, and an eye on the total super balance rules — plan this with an adviser.

    The cruder alternative is withdrawing the entire balance while alive and holding the cash personally — no super, no death benefits tax. It works, but the money then earns interest taxed at your marginal rate and loses the sheltered environment. The recontribution keeps it inside the system.

    Death benefit income streams: the option most articles skip

    A non-dependant cannot receive a death benefit as a pension — it must be a lump sum. But a dependant can choose an income stream instead (for example, a reversionary pension to a spouse, or a child pension to a minor), and the tax treatment then depends on the ages of both the deceased and the recipient:

    Deceased Recipient Taxed element Untaxed element
    60 or older Any age Tax-free Marginal rates with a 10% tax offset
    Under 60 60 or older Tax-free Marginal rates with a 10% tax offset
    Under 60 Under 60 Marginal rates with a 15% tax offset Marginal rates, no offset

    For a surviving spouse over 60 receiving a reversionary pension from a taxed fund, the taxed element is simply tax-free — often the best outcome available. One 2026-27 watchpoint: a large reversionary pension counts toward the survivor’s transfer balance and total super balance, and from 1 July 2026 it can push them over the $3 million Division 296 threshold. Our Division 296 guide works through that interaction.

    A child pension has its own quirk: it generally must be commuted — cashed out as a lump sum — by the time the child turns 25 (unless the child has a disability), and the commuted amount to a then-adult child is taxed under the non-dependant rules. Often a timing play, not a tax escape.

    Binding nominations: the three-year fuse

    A binding death benefit nomination forces your fund’s trustee to pay the benefit to the people you name, in the proportions you set. Without one, the trustee has discretion to pay any SIS dependant or your estate — and “usually honours your wishes” is doing a lot of work when $500,000 is on the table.

    The trap: most binding nominations lapse after three years. A nomination signed in 2022 and never renewed is, in 2026-27, merely advisory. Some funds (and most SMSFs) offer non-lapsing nominations — use one if yours does. Review after every major life event: marriage, divorce, a new child, or the death of a nominee. A nomination naming an ex-spouse is not automatically revoked by divorce in every fund — check yours.

    Also confirm it is validly executed: signed, dated, witnessed by two adults who are not beneficiaries, renewed before expiry. Funds reject sloppy nominations weekly, and a rejected binding nomination quietly becomes a non-binding one.

    Five mistakes that cost families real money

    1. Assuming the will covers super. It does not, unless the benefit is paid to your estate. A will that says “everything to my children equally” while the super nomination names only one child produces exactly the dispute you were trying to avoid.

    2. Letting the binding nomination lapse. Three years passes faster than you think. Put the renewal date in your calendar the day you sign it.

    3. Quoting the anti-detriment payment. Until 1 July 2017, funds could pay an extra “anti-detriment” amount that partly refunded the contributions tax — a small bonus for dependants. It was abolished in 2017. Old forum threads and stale articles still describe it as live; it is not, and planning around it in 2026-27 is planning around a ghost.

    4. Forgetting the insurance inside the super. Many funds include life cover, and the insured amount paid on death can create an untaxed element in the taxable component — taxed at 32%, not 17%, for a non-dependant. A $400,000 balance topped up by $300,000 of insurance can carry a much bigger tax bill than the balance alone suggests. Check whether your benefit includes an untaxed element before estimating the tax.

    5. Thinking the 17% hits the whole balance. It hits only the taxable component’s taxed element. The tax-free component — your after-tax contributions — always passes through untouched. Families who have made large non-concessional contributions over the years are often pleasantly surprised by how small the taxable slice actually is.

    Terminal illness: the early-release alternative

    If a member is diagnosed with a terminal medical condition — two registered medical practitioners certifying the condition is likely to result in death within 24 months — the entire super balance can be released tax-free while they are still alive, regardless of age. It is paid as a lump sum, and because the member receives it (not a beneficiary), there is no death benefits tax at all.

    It is a narrow path and nobody plans for it, but families in this situation should know it exists: releasing the balance tax-free during the member’s lifetime and gifting it directly can be far better than letting it become a taxed death benefit. The certification paperwork must be lodged with the fund before payment, and the 24-month window is strict.

    How long does a death benefit take to be paid?

    The law requires the trustee to pay “as soon as practicable” — no fixed deadline. Straightforward claims with a valid binding nomination often settle in weeks; disputed ones can take many months while the trustee investigates potential claimants, who must be notified and given a chance to object. That notification step is where delays usually come from.

    If a fund is stalling, escalate: complain to the fund first, then to the Australian Financial Complaints Authority (AFCA), which can review death benefit decisions. Consumer advocates are pushing for mandatory processing timeframes, but as of 2026-27 none exist. Keep certified copies of everything, and keep the claim reference number where your family can find it.

    Tips: getting the most to your family

    • Spouse first, almost always. A benefit paid to a surviving spouse is tax-free in full, and the spouse can then plan their own estate. The exception is a very large balance where Division 296 or transfer-balance-cap issues arise — get advice.
    • Run the recontribution numbers in your 60s. Every year you wait, earnings accrete to the taxable component. The strategy in the worked example above gets more valuable the earlier it starts, within your caps.
    • Consider the estate route for large balances to adult children. The ~2% Medicare saving is worth modelling against probate delays and costs.
    • Split nominations deliberately. If you have one dependant child and one independent adult child, nominating the dependant to receive the taxable-heavy pension and the adult child to receive a tax-free-heavy portion can equalise after-tax outcomes — the dual-pension approach.
    • Renew the binding nomination every three years and after every life event. A lapsed nomination hands your largest asset to trustee discretion.
    • Check for untaxed element and insurance on your annual statement so the eventual tax bill holds no surprises.

    FAQ

    Do I pay tax if I inherit my spouse’s super?
    No. A spouse or de facto partner is a tax dependant, so the entire death benefit — lump sum or income stream — is tax-free regardless of the components.

    Can my adult children avoid the 17% death benefits tax?
    Not after your death — the tax is mechanical. The lawful reductions all happen while you are alive: the recontribution strategy, withdrawing and gifting the balance, or leaving the benefit to a dependant first.

    Does my will control who gets my super?
    Only if the benefit is paid to your estate (by nominating your legal personal representative). Otherwise your fund’s trustee pays it under super law, following your binding nomination if you have a valid one.

    Is there inheritance tax in Australia?
    No. Australia abolished death duties decades ago and none is proposed for 2026-27. The super death benefits tax is not an inheritance tax — it is a clawback of superannuation tax concessions, and it only applies to the taxable component paid to non-dependants.

    What happens if there is no nomination at all?
    The trustee decides who receives the benefit, choosing among your SIS dependants and your estate. They will investigate and invite claims, which is why these cases take the longest. The tax treatment then follows whoever actually receives it.

    Do non-resident beneficiaries pay the tax too?
    Yes — withholding applies regardless of where the beneficiary lives. Whether their home country also taxes the receipt depends on its own laws and any tax treaty.

    The bottom line

    The super death benefits tax is one of Australia’s most expensive “optional” taxes: optional in the sense that almost every dollar of it is determined by decisions made while the member is alive — who is nominated, whether the nomination is current, how much of the balance sits in the tax-free component, and whether the benefit routes through the estate. A $500,000 balance can pass to a spouse for $0, to adult children directly for $72,250, or to adult children via the estate for $63,750 — and a few years of recontribution can cut the bill by tens of thousands more. None of it happens by accident. Check your nomination today, know your components, and if the balance is large and the beneficiaries are adult children, model the recontribution strategy before the choice is made for you. For the tools behind the numbers, try our super tax calculator and income tax calculator, and see how death benefits interact with inherited assets in our inherited property CGT guide.

  • First Home Super Saver Scheme 2026-27: FHSS Explained

    First Home Super Saver Scheme 2026-27: FHSS Explained

    Quick answer: The First Home Super Saver Scheme (FHSSS) lets you save a first-home deposit inside your super fund — up to $15,000 of voluntary contributions per financial year and $50,000 in total — then withdraw them (plus earnings) when you buy. Because concessional contributions are taxed at just 15% on the way in and the released amount gets a 30% tax offset on the way out, most savers end up roughly $8,000–$10,000 better off than stashing the same money in a savings account. But the scheme has strict timing rules, a lifetime one-release limit, and several traps the glossy guides skip.

    This guide covers how the scheme actually works in 2026-27, a full worked example on a $90,000 salary, the 85% rule that shrinks your release amount, the September 2024 timing changes almost nobody has updated their advice for, and the seven things competitors don’t tell you — alongside our salary sacrifice guide and the super calculator.

    How the FHSSS works in five steps

    1. Make voluntary contributions. Salary-sacrifice through your employer, or make personal contributions to your super fund. Only voluntary contributions count — compulsory Super Guarantee payments, spouse contributions and government co-contributions are all excluded. Contributions count in the financial year your fund receives them, not when they leave your pay.
    2. Request an FHSS determination from the ATO. When you’re ready to buy, log into myGov → ATO online services → Super → First Home Saver. The determination tells you exactly how much you’re eligible to release. You can request as many determinations as you like.
    3. Request a release. This is the irreversible step. The ATO instructs your fund to release the eligible amount; the money comes to the ATO first, tax is withheld, then the balance lands in your bank account. Allow 15–25 business days.
    4. Buy within 12 months. Sign a contract to purchase or construct a qualifying home within 12 months of your release request (a 12-month extension is available from the ATO). Notify the ATO within 28 days of signing the contract.
    5. Move in. You must genuinely intend to live in the home, and occupy it for at least 6 months within the first 12 months it’s practicable to occupy.

    (Source: ATO — First home super saver scheme.)

    The numbers that matter in 2026-27

    Rule Amount
    Voluntary contributions counted per financial year $15,000
    Total across all years $50,000
    Concessional contributions counted in release amount 85% (the other 15% was already taxed in your fund)
    Non-concessional contributions counted in release amount 100%
    Associated earnings Deemed at the ATO’s shortfall interest charge rate (not your fund’s actual returns)
    Tax on release of concessional portion Your marginal rate incl. Medicare levy, minus a 30% tax offset
    Concessional contributions cap (2026-27) $32,500 (includes SG — check the ATO, caps are indexed)
    If you don’t buy Recontribute to super, or pay a flat 20% FHSS tax on the assessable released amount

    Worked example: Sarah earns $90,000

    Sarah’s marginal rate is 30% plus the 2% Medicare levy — 32% total. She salary-sacrifices $15,000 a year for three years ($45,000 in total) into the FHSSS.

    The way in:

    • The $15,000 salary sacrifice is taxed at 15% inside her super fund: $2,250 a year.
    • Had she taken it as salary, she’d have paid 32%: $4,800 a year.
    • Tax saved on the way in: $2,550 a year, or $7,650 over three years.
    • Her SG contributions (12% of $90,000 = $10,800) plus the $15,000 sacrifice total $25,800 — comfortably under the $32,500 concessional cap, so no excess-contributions issues.

    The way out:

    • Her release amount is 85% of her $45,000 concessional contributions = $38,250, plus deemed associated earnings (say roughly $3,000 at the ATO’s deeming rate) = about $41,250 of assessable released amount.
    • Tax withheld on release: her 32% marginal rate minus the 30% FHSS offset = an effective 2%, so about $825.
    • She receives roughly $40,425 toward her deposit.

    The comparison: to pull $40,425 from after-tax savings on a 32% marginal rate, Sarah would have needed about $59,450 of pre-tax salary. She sacrificed $45,000, which cost her only $30,600 of take-home pay. Net result: the scheme has put her roughly $9,800 ahead of saving from salary — and she earned a deemed return inside super along the way. Run your own numbers in our super calculator and income tax calculator.

    Concessional or non-concessional: which contributions to use?

    The 85% rule makes the choice matter. If you salary-sacrifice $15,000 in a year, your release amount includes $12,750 of it. If you contribute $15,000 after tax, your release amount includes the full $15,000.

    But don’t stop there — the tax story flips it back. The concessional $15,000 cost you only $12,750 in contributions tax terms (15% paid in the fund), while the non-concessional $15,000 already had your full marginal rate taken out of it at salary time. For most people on 32% or above, concessional contributions win comfortably, which is why salary sacrifice is the engine of this scheme.

    The notice-of-intent trap: if you make personal contributions and want them treated as concessional (claimed as a tax deduction), you must lodge a “notice of intent to claim a tax deduction” with your fund and have it acknowledged — before you lodge your tax return for that year. Miss that notice and the contribution counts as non-concessional by default. The ATO is strict on this; it’s one of the most common ways people accidentally halve their tax benefit. See our super contribution caps guide for the full mechanics.

    The timing traps (read this before you sign anything)

    More FHSSS plans die on timing than on anything else:

    1. The 30 June boundary. Contributions count in the year your fund receives them. A salary-sacrifice contribution from your June payroll that lands in July counts for the next year — which can blow both your $15,000 FHSSS year-limit and your concessional cap. Arrange late-June sacrifices well before the deadline.
    2. Determination timing changed in September 2024. Older guides (and some accountants) still say you must get your determination before signing any contract. Since 15 September 2024, you only need the determination by settlement — you can request one after exchanging contracts as long as you don’t yet legally own the property. The window to request a release after signing also expanded from 14 days to 90 days. (Source: Spry Roughley — FHSS changes from September 2024.) If an adviser quotes you the old rule, they’re out of date.
    3. The 15–25 business day wait. The ATO recommends allowing 15–25 business days from release request to money in your account. Don’t schedule your release for the week before settlement.
    4. The 28-day notification. After signing a contract, you have 28 days to notify the ATO via myGov. Miss it and FHSS tax can apply.
    5. The 12-month clock. Sign a purchase or construction contract within 12 months of your release request (extensions to 24 months are available). After that, it’s recontribute or pay the 20% tax.

    Seven things the glossy guides don’t tell you

    1. The release can push you into a higher tax bracket

    The assessable released amount is added to your taxable income in the year of release. A $41,000 release on top of a $90,000 salary puts you at $131,000 — still under the 37% bracket threshold ($135,000), but if you’re near a bracket edge, part of your release gets taxed at the higher rate before the 30% offset applies. The ATO withholds an estimate at release time; your tax return reconciles the rest. Time your release for a lower-income year if you can.

    2. “Associated earnings” aren’t your actual earnings

    The ATO doesn’t use your fund’s real investment returns. It deems earnings at the shortfall interest charge rate (roughly 4–5% a year). In a good year your super earned more and you effectively under-claim; in a bad year your contributions “earned” money your fund never made — and the shortfall comes out of the rest of your super balance. Either way, the release amount is never less than what the formula gives you.

    3. One release per lifetime — so don’t fire early

    You can get as many determinations as you like, but you can only ever make one release request. Release $20,000 for a purchase that falls through and you can’t “top up” with another release later (you’d recontribute the $20,000 or pay the 20% tax). Only request the release when you’re genuinely about to buy.

    4. Your fund might say no

    Not every super fund participates. Check before you contribute that your nominated fund will release FHSS amounts — defined benefit funds and constitutionally protected funds are excluded entirely. Discovering your fund won’t release, after years of contributing, is a nightmare scenario that’s easy to avoid with one phone call.

    5. The 20% fallback tax isn’t as scary as it sounds — but it wipes the benefit

    If you release and never buy, you can keep the money and pay FHSS tax of 20% of the assessable released amount (not the total released). That roughly reverses the tax concessions you received. Recontributing the net amount back into super as a non-concessional contribution is usually the better option — it preserves your retirement balance and avoids the tax entirely.

    6. Owning property overseas doesn’t disqualify you

    The “never owned property” test only covers Australian real property interests — fee simple, company title, or a lease of Australian land. If you owned a home in another country, you’re still eligible (a limited financial-hardship exception also exists for those who lost Australian property). Almost no consumer guide mentions this.

    7. It stacks with other first-home help

    Your FHSS release is just deposit money — it combines freely with stamp duty concessions (see our NSW & VIC first home buyer guide) and the Australian Government’s 5% Deposit Scheme, which removed its place limits from 1 October 2025. Stacking a $40,000 FHSS release with a 5% deposit scheme and a stamp duty exemption is how many buyers get over the line. Estimate your repayments with our mortgage calculator.

    Common mistakes

    • Contributing more than $15,000 in one year expecting it all to count — only $15,000 of that year’s contributions is eligible for release.
    • Counting SG contributions. Your employer’s compulsory super doesn’t count, no matter how much you wish it did.
    • Forgetting the notice of intent for personal deductible contributions (see above).
    • Salary-sacrificing in June without checking the money lands before 30 June.
    • Blowing the concessional cap. SG + salary sacrifice over $32,500 in 2026-27 means excess contributions taxed at your marginal rate — which can erase the FHSSS benefit. See our caps guide.
    • Requesting the release too early — remember, one release per lifetime and a 12-month clock starts ticking.
    • Signing a contract and forgetting the 28-day ATO notification.

    Tips to get the most from the scheme

    • Start early, even with small amounts. The $50,000 total needs at least four financial years at the $15,000 yearly cap — plan backwards from when you want to buy.
    • Couples, double it. Each eligible person gets their own $50,000 — that’s a $100,000 combined deposit pool. Siblings or friends buying together can each use it too.
    • Prefer salary sacrifice over personal contributions if your employer supports it — no notice-of-intent paperwork, and the tax is handled at source.
    • Keep a contribution spreadsheet. Track each voluntary contribution by financial year against the $15,000 limit. The ATO’s determination should match your records — if it doesn’t, query it before requesting release.
    • Get a determination early as a sanity check. Determinations are free and unlimited — use one to confirm your eligible amount before you’re under contract pressure.

    Frequently asked questions

    Can I use the FHSSS for an investment property?

    No. The property must be residential premises in Australia that you genuinely intend to occupy — at least 6 months within the first 12 months it’s practicable to live in. Houseboats, motor homes and vacant land (unless you’re building on it) are all excluded.

    Can I withdraw contributions in the same financial year I made them?

    Yes. Any voluntary contribution made from 1 July 2017 can be included in your determination, up to the date you request it. There’s no minimum holding period.

    What happens to my super balance after the release?

    Only the FHSS amounts leave. Everything else — your SG contributions, their earnings, and any voluntary contributions beyond the release — stays in super for retirement. If the deemed earnings exceed what your FHSS contributions actually earned, the difference comes from your remaining balance.

    Does using the FHSSS affect my other super?

    Released amounts don’t count against your contribution caps again — the caps were already applied when the contributions went in. But the released assessable amount does count as taxable income in the release year, which can affect HELP repayments, the Medicare levy surcharge and family payments.

    I’ve already exchanged contracts — is it too late?

    Not necessarily. Since 15 September 2024, you can still request a determination as long as you haven’t become the legal owner (settlement usually transfers ownership), and you then have 90 days from the contract date to make a valid release request. Get moving immediately — the old “must apply before signing” rule no longer applies, but the windows are still tight.

    Is the FHSSS worth it compared to just saving in a bank account?

    For anyone on a marginal rate above 15% — which is almost everyone working full-time — the maths favours the scheme, as the worked example shows. The main costs are complexity and the fact that your money is locked in super until you buy. If your purchase is more than a year or two away, it’s one of the most tax-effective savings vehicles available for a deposit.

    The bottom line

    The First Home Super Saver Scheme is genuinely one of the best deposit-building tools in the Australian tax system: $15,000 a year and $50,000 total of your own money, taxed at 15% going in and roughly your marginal rate minus 30% coming out. Our worked example put a $90,000 earner nearly $9,800 ahead over three years. The scheme punishes haste, though — respect the 30 June boundary, get the determination sorted before settlement, lodge your notices of intent, and only ever pull the release trigger when you’re truly ready to buy. For the contribution mechanics, pair this guide with our salary sacrifice deep-dive and check your numbers in the super calculator.